

Circular 90/2026/TT-BTC on tax registration was issued by the Ministry of Finance on June 30, 2026, takes effect from July 1, 2026, and replaces Circular 86/2024/TT-BTC. Guided by the Vietnam Tax Administration Law, the new Circular significantly adjusts the procedures for tax registration applicable to enterprises, organizations, business households, individuals, and entities doing business on digital platforms. Notably, it strengthens the use of electronic data and personal identification numbers, adds new groups of registrants, and changes the procedures for changing and restoring tax identification number validity. In the article below, Viet An Law Firm will help clients better understand the new regime on tax registration in Vietnam under Circular 90/2026/TT-BTC.
When does Circular 90/2026/TT-BTC take effect in Vietnam?
- Circular 90/2026/TT-BTC was issued on June 30, 2026, and officially applies from July 1, 2026; it fully replaces Circular 86/2024/TT-BTC on tax registration.
- The Circular is built based on the Vietnam Tax Administration Law No. 108/2025/QH15 and Decree 252/2026/ND-CP, while updating new regulations on tax administration, enterprise registration, business households, e-commerce and identification information management.
Notable new tax registration rules in Vietnam: Circular 90/2026/TT-BTC compared with Circular 86/2024/TT-BTC
Compared with Circular 86/2024/TT-BTC, Circular 90/2026/TT-BTC introduces many practical changes. Key points that enterprises, business households and individuals should pay particular attention to include:
| Content | Circular 86/2024/TT-BTC | Circular 90/2026/TT-BTC |
| Tax registrants | Regulated under the previous management mechanism | Adds and clarifies many groups doing business on digital platforms |
| Electronic dossiers | Available but not as extensive as under the new regulations | Adds electronic methods and electronic authentication |
| Tax registration certificate | Paper version and re-issuance procedure available | Shifts focus to the digitally signed electronic version; re-issuance procedure abolished |
| Change of address | Fulfillment of obligations at the place of departure required in some cases | Removes the requirement to fulfill obligations before relocating |
| Personal tax identification number | In the process of conversion to personal identification numbers | Enhanced integration and cross-checking with the national population database |
| Business locations of households and individuals | No separate mechanism as under the new regulations | Notification procedure when a new business location arises |
| Termination of tax identification number | Regulated under the previous cases | Many new cases added, especially for digital platforms and foreign suppliers |
| Tax identification number lookup | More limited scope of information | Expanded information available for lookup on the system |
Additional entities required to register for tax in Vietnam in connection with digital platform business
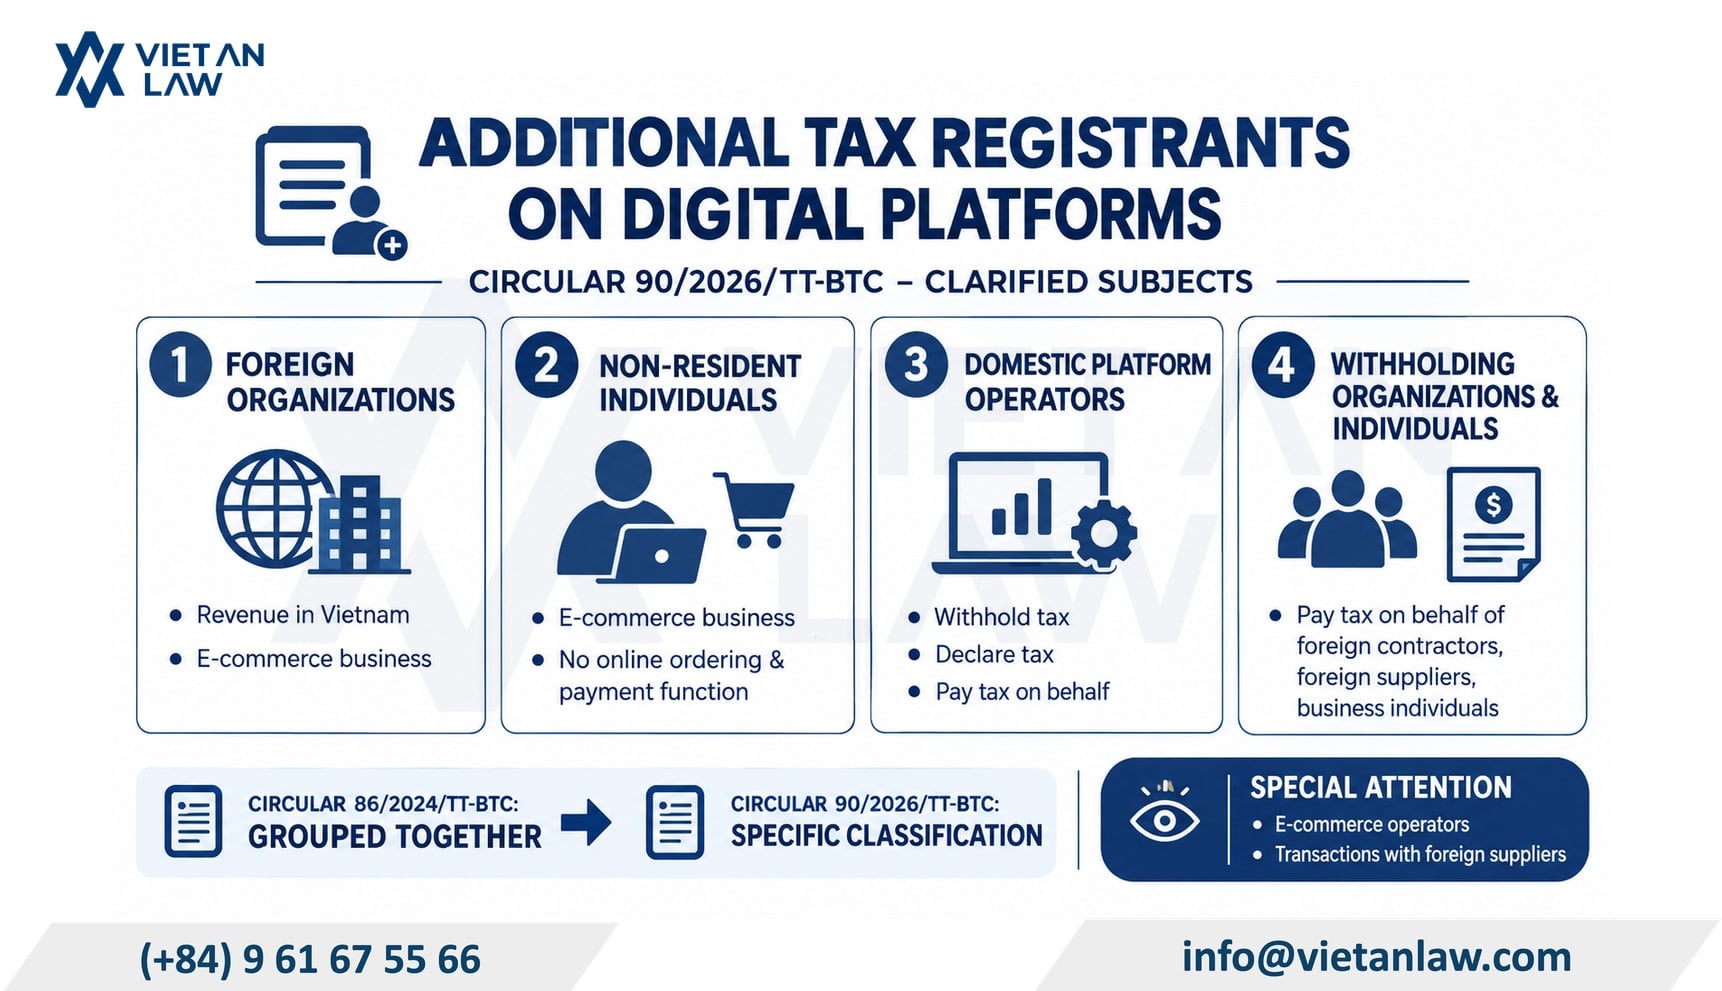
One notable change is that Circular 90/2026/TT-BTC further clarifies the entities subject to registering for tax in the digital business environment.
These include:
- Foreign organizations earning revenue in Vietnam through business activities on e-commerce platforms;
- Non-resident individuals doing business on e-commerce platforms without online ordering and payment functions;
- Domestic e-commerce platform and digital platform operators that are required to withhold, declare and pay tax on behalf of others;
- Organizations and individuals withholding and paying tax on behalf of foreign contractors, foreign suppliers or business individuals as prescribed.
Compared with Circular 86/2024/TT-BTC, the replacing regulation, Circular 90/2026/TT-BTC, classifies each group of entities more specifically instead of grouping them together.
This is a point of particular interest for enterprises operating e-commerce or digital platforms or transacting with foreign suppliers.
Expanded electronic tax registration procedure in Vietnam under Circular 90/2026/TT-BTC
Circular 90/2026/TT-BTC clearly adds methods of receiving electronic tax registration dossiers via:
- The National Public Service Portal;
- The national identification application;
- The tax administration information system.
Dossiers may be electronically authenticated, including biometric information, in accordance with regulations on electronic identification and authentication and the tax authority’s implementation roadmap.
This new point is in line with the shift from paper dossiers to electronic transactions in tax administration.
However, it should be noted that the application of all forms of electronic transactions in tax registration still follows the tax authority’s roadmap; this should not be understood to mean that every procedure must immediately be carried out through a single electronic method.
Personal income tax and cases requiring tax identification number registration in Vietnam
- Besides enterprises, business households and organizations, registering for tax as an individual is also a matter to note when applying the new regulations. Certain individuals with personal income tax obligations must register for tax and update their identification information and dependant information as prescribed.
- In particular, individuals with taxable income, individuals with dependants registering for family circumstance deductions, or those otherwise obliged to register for tax need to correctly determine the applicable category and the timing of the procedure. Tax identification number registration is now more closely connected with personal identification numbers and the national population database, so individuals must ensure their registered information is consistent with their identification documents.
- Specific regulations on personal income tax, dependants and cases requiring tax registration under Decree 253/2026/ND-CP can be found in Viet An Law Firm’s article on Decree 253/2026/ND-CP guiding the Law on Personal Income Tax. https://luatvietan.vn/huong-dan-luat-thue-thu-nhap-ca-nhan.html
Cases where tax identification numbers are processed after 180 days upon enterprise dissolution in Vietnam
- A practical situation to note is where the tax authority has issued a notice of completion of tax obligations for an enterprise to carry out dissolution procedures, but more than 180 days after the tax authority receives information on the dissolution decision, it has not yet received information on the completion of dissolution from the business registration authority.
- In this case, the tax authority may send a written request to the business registration authority to update the enterprise’s legal status to “dissolved”, as a basis for the tax authority to terminate the validity of the tax identification number on the system.
- This regulation helps limit situations where dissolution dossiers are left “pending” for a long time because information between the business registration authority and the tax authority is not updated synchronously.
Key forms under the new regime on tax registration in Vietnam under Circular 90/2026/TT-BTC
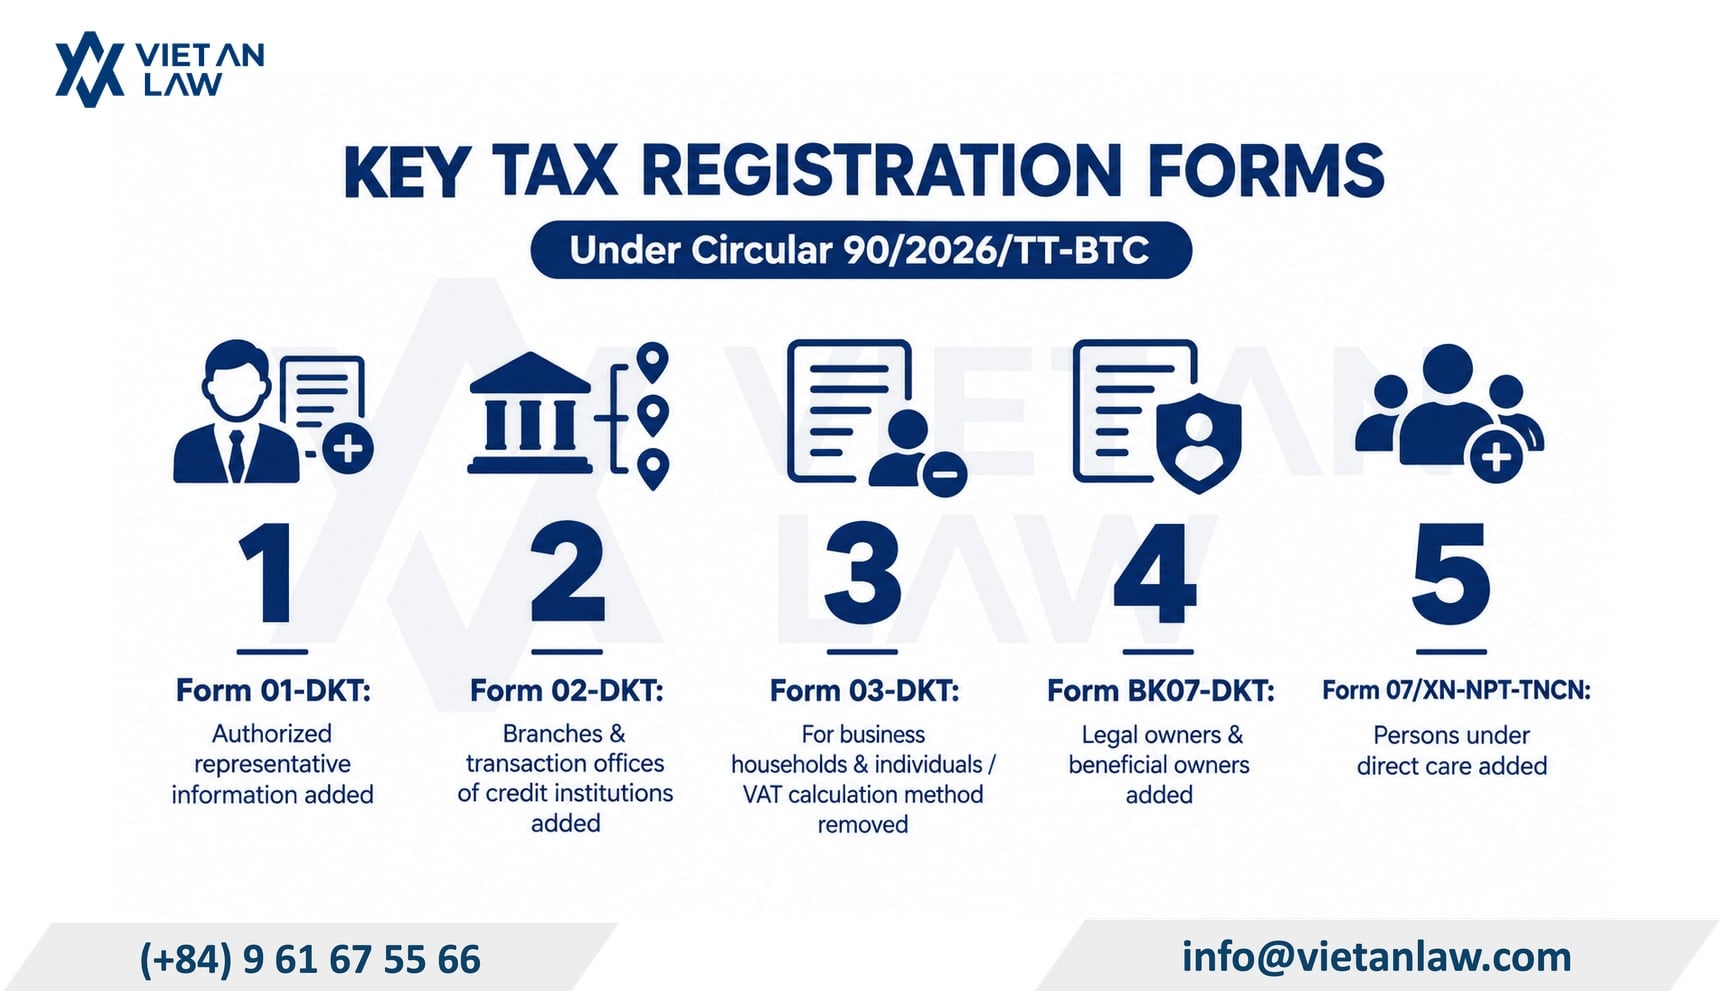
The new Circular basically inherits the form system of Circular 86/2024/TT-BTC but adjusts many indicators and adds forms for new subjects.
Some notable points:
- Form 01-DKT adds information on the authorized representative;
- Form 02-DKT adds cases of branches and transaction offices of credit institutions;
- Form 03-DKT for business households and business individuals is adjusted, removing the indicator on the VAT calculation method;
- Addition of Form BK07-DKT on legal owners and beneficial owners of foreign companies with branches or representative offices in Vietnam;
- Addition of Form 07/XN-NPT-TNCN on persons under direct care;
- Removal of the form requesting re-issuance of the tax registration certificate/TIN notice, as the re-issuance procedure has been abolished.
Enterprises, business households and individuals must use the correct forms under the new tax registration rules of Circular 90/2026/TT-BTC for procedures arising from July 1, 2026.
Frequently asked questions
Do individuals with multiple tax identification numbers have to cancel the old ones?
Individuals need to update their personal identification number so that the tax authority can integrate their tax identification numbers into the personal identification number and consolidate tax data. Invoices, documents and tax dossiers previously made using the old tax identification numbers remain valid as prescribed.
Must a business household opening an additional business location notify the tax authority?
Yes. When a business household or business individual has an additional business location outside its head office, it must notify the tax authority directly managing the head office under the new regulations.
Does an enterprise changing its address still have to fulfill tax obligations at the old tax authority before relocating?
There is no longer a general requirement to fulfill tax obligations at the tax authority of the place of departure before changing the address. However, if the taxpayer is classified as high-risk and subject to an on-site inspection, the prescribed inspection procedure must still be followed.
How is tax registration carried out if the tax system cannot connect to population data?
When the connection to population data is interrupted, you need to fully declare your information and attach a copy of a valid identity card or citizen identity card for the tax authority to process the dossier.
What additional requirements apply to the tax registration dossier for dependants?
Circular 90/2026/TT-BTC adds documents for certain cases of tax registration for dependants, including the declaration of persons under direct care using Form 07/XN-NPT-TNCN and documents proving dependants in accordance with personal income tax regulations. Clients can learn more about the Decree 253/2026/ND-CP: Guide to Personal Income Tax Law in Vietnam 2025 in Viet An Law Firm’s article at: https://vietanlaw.com/decree-253-2026-nd-cp-guide-to-personal-income-tax-law-in-vietnam/
Tax, accounting & payroll services of Viet An Law Firm in Vietnam
- The new regime on tax registration in Vietnam under Circular 90/2026/TT-BTC not only changes forms but also directly affects the tax registration procedure, changes of information, and the termination and reinstatement of tax identification numbers of enterprises, business households and individuals.
- In practice, cases such as changing a company address, changing the head of a business household, adding a business location, synchronizing personal identification numbers, terminating a TIN or applying to restore tax identification number validity may simultaneously involve multiple authorities and data systems.
- Viet An Law Firm provides tax, accounting & payroll services, supporting enterprises in reviewing dossiers, carrying out tax procedures and handling issues arising during their operation.
- Enterprises, business households or individuals facing difficulties when applying Circular 90/2026/TT-BTC and Decree 252/2026/ND-CP may contact Viet An Law Firm for advice and support tailored to their specific case.
Clients who wish to receive more detailed advice on the above content, please contact Viet An Law Firm for the best support!