

VAT refund for foreigners in Vietnam under Circular 84/2026/TT-BTC is a legal framework that every retailer, commercial bank and international visitor to Vietnam should understand before making purchases that give rise to a refund entitlement. From July 1, 2026, the entire process of VAT refund for foreigners and Vietnamese people residing abroad who buy goods in Vietnam and carry them out upon departure operates under a completely new mechanism, built on an interconnected electronic data system linking customs authorities, tax authorities, commercial banks and retailers. Circular 84/2026/TT-BTC also fully replaces two documents that had been applied for more than a decade, namely Circular 72/2014/TT-BTC and Circular 92/2019/TT-BTC. In the article below, Viet An Law Firm, a law firm in Vietnam offering a full tax and accounting service to enterprises, analyzes the core contents of the Circular in detail and places them in the general legal framework together with Circular 89/2026/TT-BTC guiding the Law on Tax Administration and Decree 252/2026/ND-CP.
What is Circular 84/2026/TT-BTC? Legal basis and scope of VAT refund in Vietnam
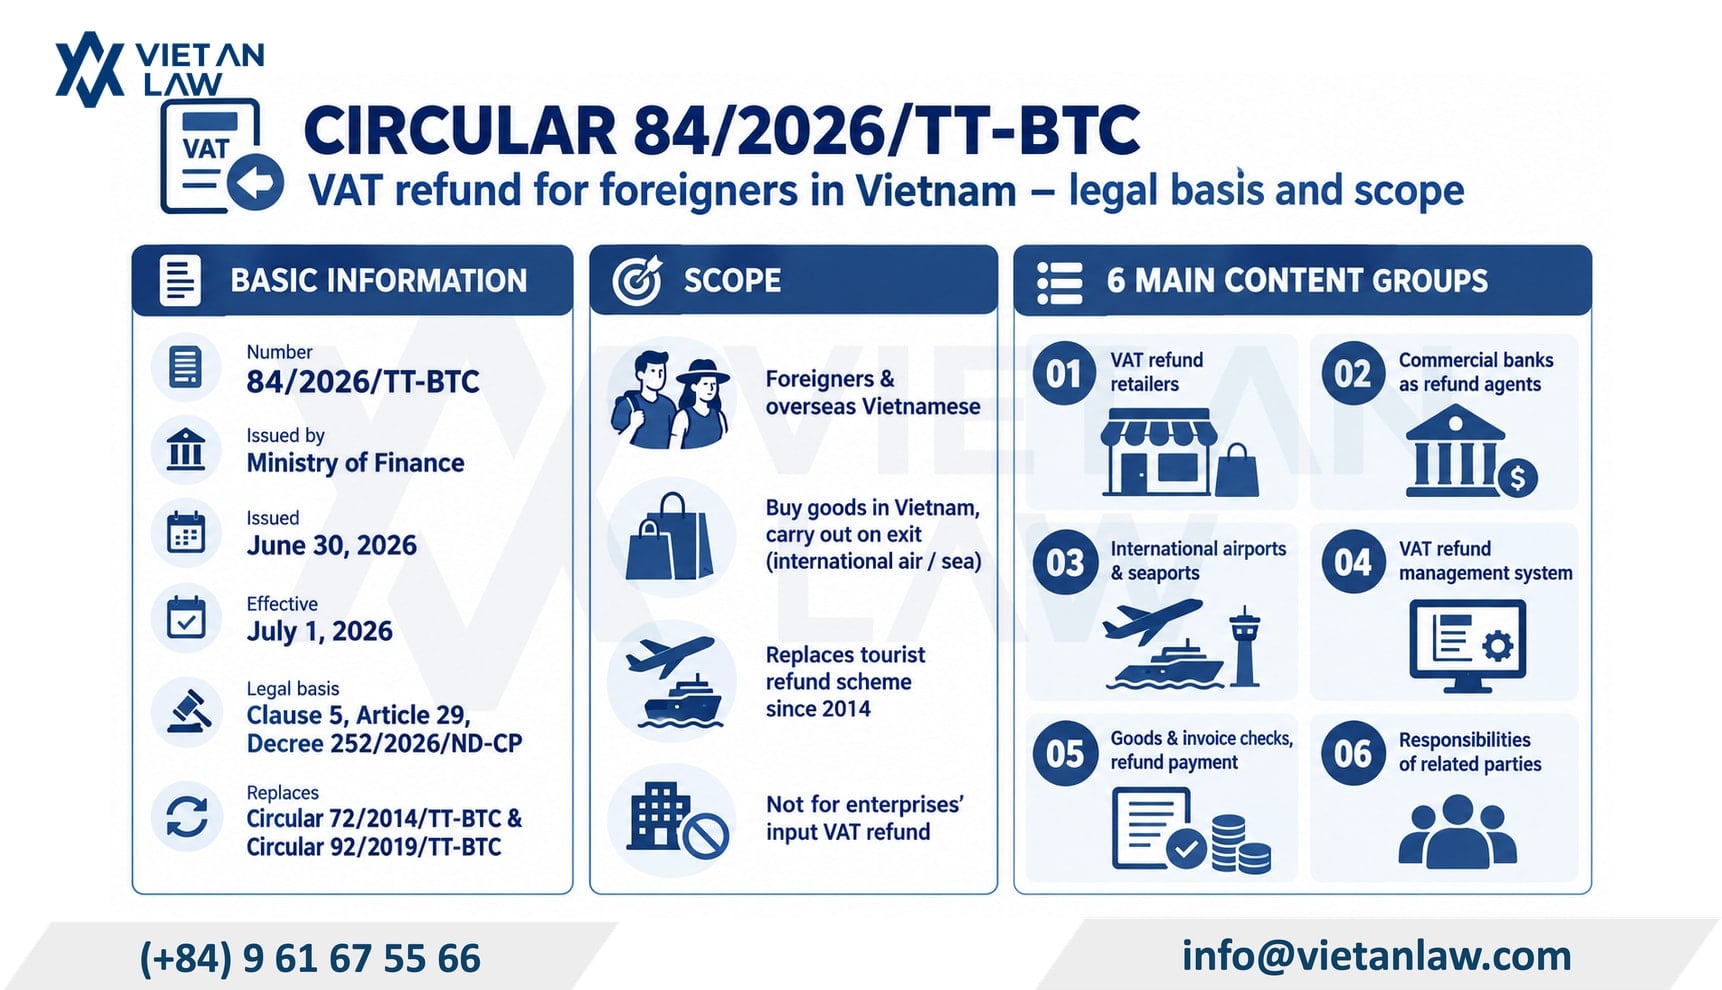
Key facts, scope and six content groups of the new refund scheme for departing shoppers
Basic information about the Circular
VAT refund for foreigners in Vietnam under Circular 84/2026/TT-BTC was issued by the Ministry of Finance on June 30, 2026 and officially took effect on July 1, 2026. The table below summarizes the basic information of the document for easy reference:
| Information | Details |
| Number | 84/2026/TT-BTC |
| Issuing authority | Ministry of Finance |
| Date of issuance | June 30, 2026 |
| Effective date | July 1, 2026 |
| Legal basis | Clause 5, Article 29 of Decree 252/2026/ND-CP |
| Replaced documents | Circular 72/2014/TT-BTC and Circular 92/2019/TT-BTC |
The Circular was issued to detail Clause 5, Article 29 of Decree 252/2026/ND-CP dated June 30, 2026 of the Government, which details a number of articles and measures to organize and guide the implementation of the Law on Tax Administration.
Scope of regulation – clarifying a common misunderstanding
Many people easily confuse two completely different concepts: VAT refund on goods purchased abroad (which does not exist in this sense under Vietnamese tax law) and VAT refund for foreigners purchasing goods in Vietnam. Circular 84/2026/TT-BTC only governs the second case: foreigners and Vietnamese people residing abroad who buy goods in Vietnam and carry them out when departing via international air or sea routes. This regulation replaces the tourist shopping refund mechanism that has existed since 2014. It should be clearly distinguished from the input VAT refund for enterprises under the general provisions of the Law on Value-Added Tax – that is a different legal category outside the scope of this Circular.
Six groups of content governed by the Circular
Circular 84/2026/TT-BTC covers six main groups of content:
- Standards, dossiers and procedures for selecting, adjusting and terminating VAT refund retailers;
- Standards and procedures for selecting and terminating commercial banks acting as VAT refund agents;
- Selection, suspension and termination of VAT refund application at international airports and international seaports;
- Access to, exchange and connection of information on the VAT refund management system for foreigners;
- Locations for inspecting goods, checking invoices cum refund declarations and paying VAT refunds;
- Responsibilities and powers of relevant agencies, organizations and individuals in implementing VAT refunds.
The VAT refund management system for foreigners in Vietnam – the backbone of the Circular
Authority developing and operating the System
Under Article 3 of Circular 84/2026/TT-BTC, the VAT refund management system for foreigners is developed, managed and operated by the Customs Department. The System integrates, stores and exchanges information among four groups of entities: customs authorities, tax authorities, commercial banks and VAT refund retailers.
Legal validity of electronic data
Notably, data on the System is considered a data message with legal validity under the law on electronic transactions. This provision significantly reduces paperwork while shortening the time needed to cross-check information at border checkpoints, making the tax refund process in Vietnam faster and more transparent.
Connection with the tax authority’s e-invoice system
The VAT refund management system is also directly connected to the tax authority’s e-invoice system to check and cross-check invoices cum refund declarations in real time. The list of shared data and input information criteria of the System is specified in Appendix II of the Circular. The tax refund process in Vietnam can be visualized in the following sequence: the retailer enters data into the Customs refund system, the data is cross-checked against the tax authority’s e-invoice system, and the commercial bank acting as refund agent then receives the information to pay the client before departure.
Rights and obligations of foreigners in the VAT refund upon exit procedure in Vietnam
Responsibilities of clients under Article 4
Foreigners and Vietnamese people residing abroad are responsible for checking the information on the invoice cum refund declaration issued by the store, and for presenting their passport, the actual goods and related documents as required upon request.
Mandatory deadline: 30 minutes before departure
This is the most practical regulation that every traveler should remember: passengers must submit the invoice cum refund declaration and present the goods to the customs authority no later than 30 minutes before the aircraft or ship departs so that they can be inspected before exit. This deadline aims to ensure accurate verification of goods while avoiding congestion at checkpoint inspection areas – a common complaint under the old mechanism.
5-step checklist for foreign visitors completing VAT refund upon exit
To ensure a smooth tax refund for foreigners, visitors should follow this sequence: (1) buy goods at a store recognized by the tax authority as a VAT refund retailer; (2) request the invoice cum refund declaration right at the counter; (3) carefully check the information on the invoice before leaving the store; (4) complete customs inspection at least 30 minutes before departure; (5) receive the refund at the payment point or through the designated agent bank at the international airport or seaport.
Conditions for retailers providing VAT refund service in Vietnam under Circular 84/2026
Four mandatory standards under Article 10
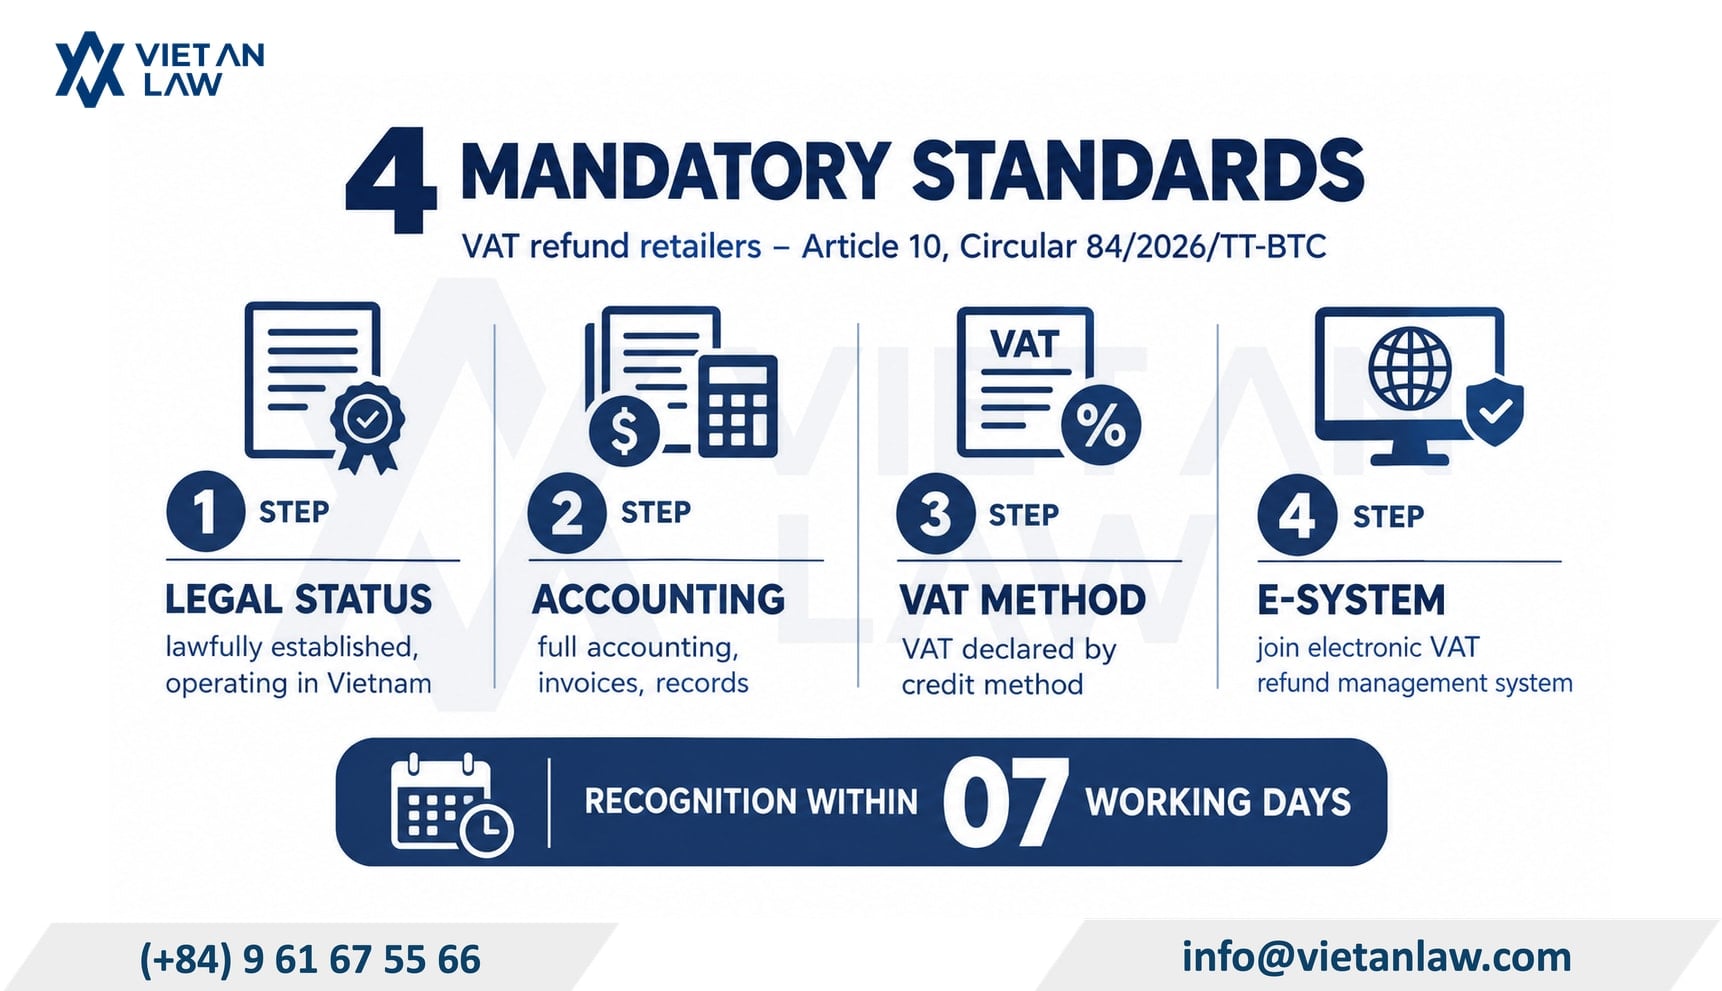
Four conditions a retailer must meet at the same time to sell goods eligible for refund
To sell goods eligible for VAT refund, an enterprise must simultaneously meet four conditions: being lawfully established and operating in Vietnam; fully complying with accounting, invoice and document regimes as prescribed; declaring VAT by the credit method; and committing to join the electronic VAT refund management system.
Time limit for processing registration dossiers
After receiving a complete and valid dossier, the tax authority is responsible for reviewing and recognizing the VAT refund retailer within 07 working days – a relatively short time limit compared with many other tax administrative procedures, reflecting the Ministry of Finance’s orientation toward procedural reform.
Operational obligations after recognition under Article 5
VAT refund retailers must fully enter information on invoices cum refund declarations into the System, digitally sign and transmit the data to the customs authority, and print the invoice for the foreigner. In addition, they must register to use e-invoices, submit quarterly reports on their refund sales activities and assist foreigners with refund procedures when necessary.
Handling technical incidents of the System
If the System encounters an incident, enterprises may issue temporary paper invoices but must update all data on the System as soon as it resumes normal operation. Enterprises should proactively develop internal backup procedures and assign dedicated staff to cross-check and update data to avoid the risk of delays or inaccurate information.
Role of commercial banks acting as a VAT refund agency in Vietnam
Under Article 12, a commercial bank wishing to act as a refund agent must be permitted to conduct foreign exchange activities and provide foreign exchange services in accordance with the law. After meeting the conditions and being approved by the Customs Department, the bank is granted an account to access the System to perform four groups of VAT refund agency tasks: advancing refund money to clients, checking dossiers, making payments and storing refund dossiers as prescribed. The advance mechanism allows travelers to receive money right at the departure area without waiting for a lengthy processing procedure, thereby helping improve the shopping and tourism experience in Vietnam.
Circular 89/2026/TT-BTC and Decree 252/2026/ND-CP – the overarching legal framework in Vietnam to read in parallel
Three-tier relationship of legal documents
To fully understand the position of Circular 84/2026/TT-BTC in the current tax legal system, it should be placed in a three-tier relationship: the Law on Tax Administration 2025 (No. 108/2025/QH15) is the original document; Decree 252/2026/ND-CP guiding the Law on Tax Administration details a number of articles and measures to implement the Law; and at the lowest tier, two specialized guiding circulars take effect in parallel on the same day, July 1, 2026, namely Circular 84/2026/TT-BTC (specializing in VAT refunds for foreigners) and Circular 89/2026/TT-BTC (providing overall guidance on tax administration).
Notable points of Circular 89/2026/TT-BTC guiding the Law on Tax Administration and Decree 252/2026/ND-CP
Circular 89/2026/TT-BTC was issued by the Minister of Finance on June 30, 2026, effective from July 1, 2026, detailing a number of articles, clauses and points assigned under the Law on Tax Administration and Decree 252/2026/ND-CP. The Circular fully or partially repeals many previous documents, notably Circular 80/2021/TT-BTC, Circular 19/2021/TT-BTC, Circular 103/2014/TT-BTC and Circular 92/2015/TT-BTC.
In terms of content, Article 9 of the Circular specifies in more detail electronic dossiers and documents in electronic tax transactions; Article 99 replaces a number of tax declaration forms applicable to business households and individual businesses with new forms issued in Appendix I of the Circular. A change of wide interest is the abolition of monthly personal income tax declaration for income from salaries and wages, reducing the procedural burden for both enterprises and employees.
Transitional provisions – the most confusing part
The table below summarizes the key transitional points that enterprises should note when applying these two circulars at the same time:
| Content | Before July 1, 2026 | From July 1, 2026 |
| Tax declaration dossiers for tax periods before July 1, 2026 | Old forms apply | Continue using the forms applicable before Circular 89/2026/TT-BTC took effect (Article 100) |
| Decisions and notices issued by tax authorities before the effective date | As issued | Continue to be implemented as issued until their expiry or termination of validity |
| Customs electronic data processing system and refund system connection not yet completed | Circular 92/2019/TT-BTC applies | Certain transitional provisions of Circular 92/2019/TT-BTC continue to apply until the System is fully put into use |
Therefore, enterprises and taxpayers should not immediately apply all new forms and procedures to every tax period, but should accurately determine the tax period and the time the obligation arises in order to select the applicable document.
What should enterprises in Vietnam do now? A checklist of 6 preparation tasks
Before the new regulations operate stably, retailers and commercial banks should take the following steps, ideally with support from a professional tax and accounting service:
- Review the conditions under Article 10 of Circular 84/2026/TT-BTC and prepare a registration dossier if wishing to sell goods eligible for VAT refund;
- Check that the internal e-invoice system is ready for digital signing and data transmission to the VAT refund management system;
- Assign a dedicated focal point for updating data and handling system incidents;
- Schedule quarterly reports in line with the tax authority’s requirements;
- Train sales staff on their obligation to advise clients, especially on the 30-minute deadline before departure;
- Review the tax declaration forms in use under Circular 89/2026/TT-BTC to apply them correctly to tax periods arising from July 1, 2026.
Frequently asked questions
Does Circular 84/2026/TT-BTC regulate VAT refund on goods purchased abroad or in Vietnam?
This point should be clarified from the outset: Circular 84/2026/TT-BTC regulates VAT refund on goods bought in Vietnam by foreigners and Vietnamese people residing abroad and carried out upon departure. In other words, it is a tax refund for foreigners and overseas Vietnamese shopping in Vietnam, not a regulation on purchases made abroad.
When does Circular 84/2026/TT-BTC take effect and which documents does it replace?
The Circular takes effect from July 1, 2026, fully replacing Circular 72/2014/TT-BTC and Circular 92/2019/TT-BTC as the legal basis for VAT refund in Vietnam for departing shoppers.
Does Circular 84/2026/TT-BTC provide a tax refund for overseas Vietnamese?
Yes. The Circular applies to both foreigners and Vietnamese people residing abroad who buy goods in Vietnam and carry them out upon departure, so the tax refund for overseas Vietnamese follows the same procedure as for foreign visitors.
How long before departure must foreign visitors complete customs procedures?
No later than 30 minutes before the aircraft or ship departs, visitors must submit the invoice cum refund declaration and present the goods for customs inspection.
Do tax periods arising before July 1, 2026 use the forms under Circular 89/2026/TT-BTC or the old forms?
Under the transitional provisions in Article 100 of Circular 89/2026/TT-BTC, tax declaration dossiers for tax periods before July 1, 2026 continue to use the forms applicable before the Circular took effect.
VAT refund for foreigners in Vietnam under Circular 84/2026/TT-BTC marks an important shift toward comprehensive digitalization and a clear allocation of responsibilities among the parties involved in the refund process. If clients have any questions regarding Circular 84/2026/TT-BTC and Circular 89/2026/TT-BTC or need a VAT refund service, please contact Viet An Law Firm, a reputable law firm in Vietnam, for the best support!