

Personal income tax reduction in Vietnam 2026 is one of the notable support policies passed by the National Assembly in Resolution 43/2026/QH16 on reducing personal income tax and corporate income tax for individuals and enterprises. Accordingly, a resident individual with income from business whose annual revenue in 2026 and 2027 does not exceed VND 10,000,000,000 is granted a 30% reduction of the PIT payable for the corresponding tax period. Together with other tax incentives, the policy takes effect from August 24, 2026, and applies to the tax periods of 2026 and 2027. In the article below, Viet An Law Firm will provide detailed information on this support policy.
Overview of the personal income tax reduction in Vietnam 2026
Resolution 43/2026/QH16 was passed by the National Assembly on August 24, 2026 at the First Extraordinary Session of the 16th National Assembly and takes effect from August 24, 2026.
For PIT, Article 1 of the Resolution provides for a 30% reduction of the PIT payable on income from business of a resident individual that satisfies the revenue condition.
The policy applies to the tax periods of 2026 and 2027.
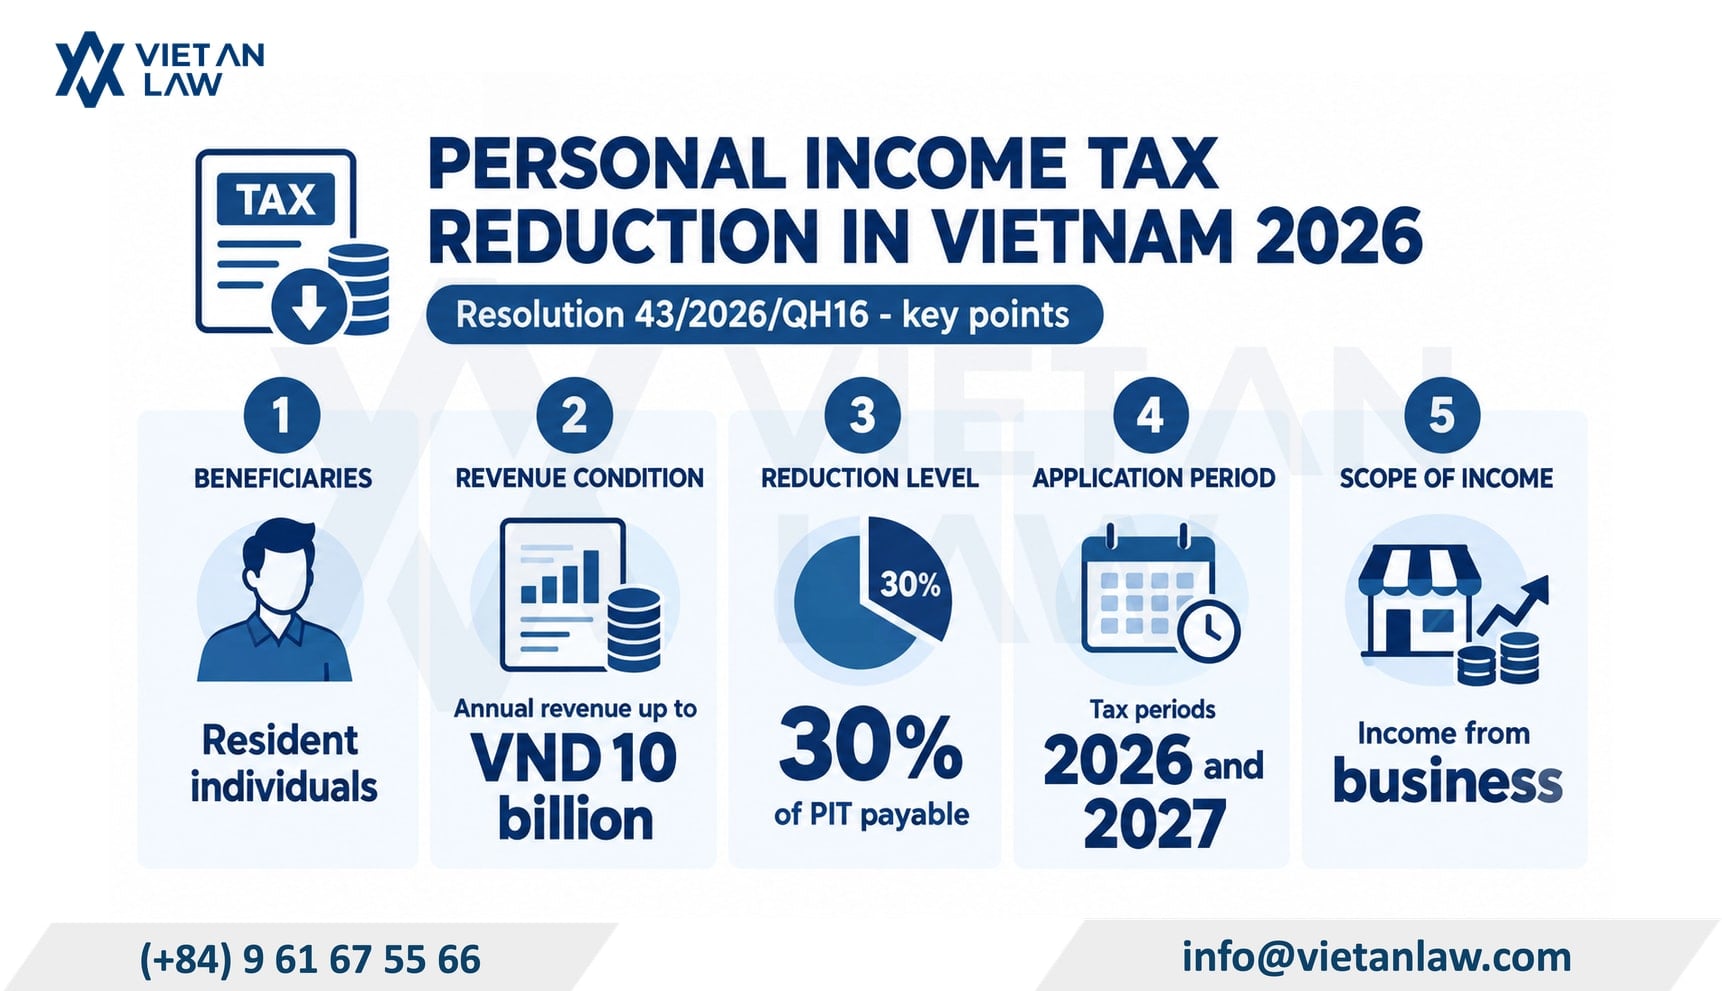
Specifically:
| Item | Provision |
| Legal document | Resolution 43/2026/QH16 |
| Date of issuance | August 24, 2026 |
| Effective date | August 24, 2026 |
| Beneficiaries | Resident individuals with income from business |
| Revenue condition | Annual revenue not exceeding VND 10,000,000,000 |
| Reduction level | 30% of the PIT payable |
| Application period | Tax periods of 2026 and 2027 |
| Scope of income | Income from business |
How is the PIT reduction in Vietnam provided for in 2026?
Article 1 of Resolution 43/2026/QH16 provides:
“Article 1. Reduction of personal income tax and corporate income tax
1. A 30% reduction of the amount of PIT payable for the tax periods of 2026 and 2027 shall apply to income from business of resident individuals whose annual revenue in 2026 and 2027 does not exceed VND 10,000,000,000.”
This provision may be understood to mean that, in order to reduce personal income tax, three basic conditions must be satisfied:
- The taxpayer must be a resident individual.
- The individual must have income from business activities.
- Annual revenue in 2026 and 2027 must not exceed VND 10,000,000,000.
When these conditions are met, the individual is entitled to a 30% reduction of the PIT payable for the corresponding tax period.
A point to note is that the Resolution uses the criterion of “annual revenue”, while the amount reduced is the “amount of PIT payable”. Therefore, it should not be understood that an individual receives a 30% reduction in revenue or a 30% reduction in the tax rate.
Who is entitled to the 30% PIT cut in Vietnam?
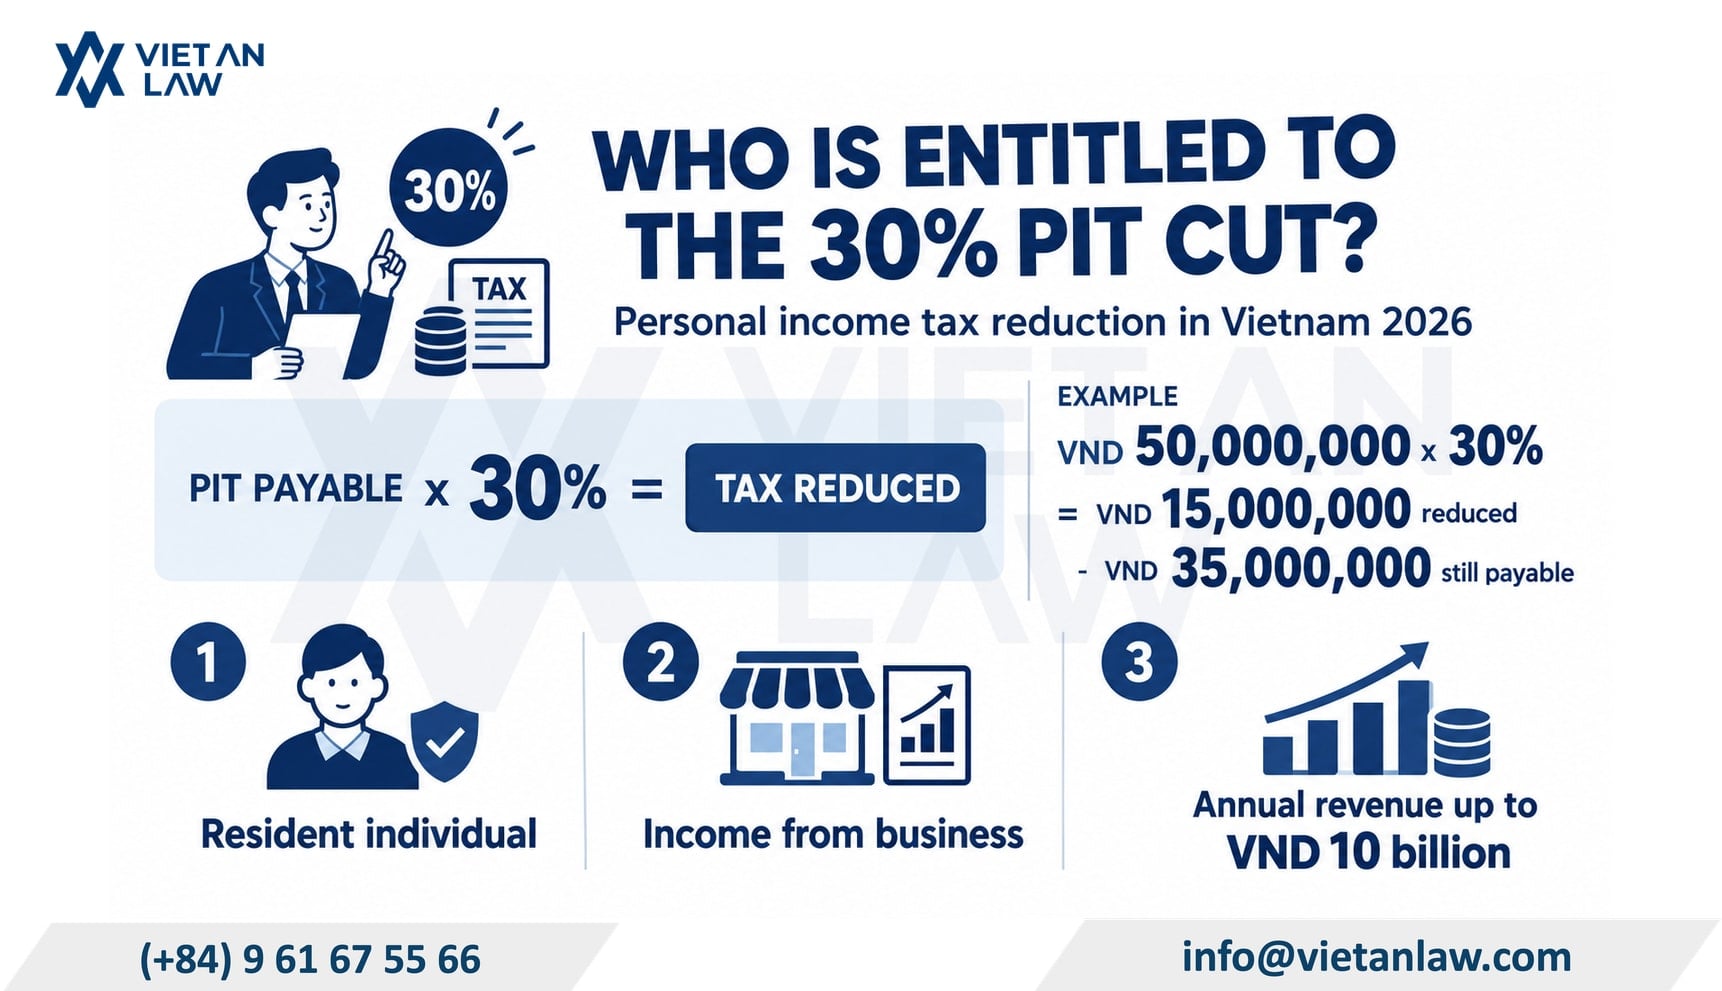
The beneficiaries of the reduction policy under Resolution 43/2026/QH16 are resident individuals with income from business who satisfy the revenue condition.
Accordingly, the policy targets individuals who directly carry out business activities, especially those whose revenue does not exceed VND 10,000,000,000 per year.
The individual must be a resident individual
The first condition is that the individual falls within the category of resident individuals under the PIT laws of Vietnam.
Therefore, when determining whether the policy can be applied, the residency status of the individual must be correctly determined under the tax laws, rather than relying solely on the fact that the individual is carrying out business activities in Vietnam.
There must be income from business
The Resolution provides for a tax reduction applicable to income from business.
Therefore, not all income of a resident individual is reduced by 30% under this policy.
For example, an individual with salaries, wages or other income subject to PIT is not automatically granted a 30% reduction merely because that individual also carries out business activities.
The scope of the policy must be determined according to the income from business that falls within the scope provided for in the Resolution.
Annual revenue not exceeding VND 10,000,000,000
The next of the PIT reduction conditions is that annual revenue in 2026 and 2027 must not exceed VND 10,000,000,000.
Accordingly, for each tax period, the individual must determine the revenue of the corresponding year in order to consider whether the conditions for application are met.
The fact that the revenue of one year satisfies the condition does not mean that the individual is automatically entitled to the tax reduction for all subsequent years.
How much is the personal tax reduction in Vietnam for 2026?
Under Resolution 43/2026/QH16, the reduction is 30% of the PIT payable for the tax periods of 2026 and 2027 if the individual fully satisfies the conditions.
It is particularly important to distinguish: a 30% reduction of the tax payable ≠ a 30% reduction of revenue ≠ a 30% reduction of income.
For example:
Assume that a business individual fully satisfies the conditions and the PIT payable for the tax period of 2026 is VND 50,000,000.
Tax reduced: VND 50,000,000 × 30% = VND 15,000,000.
Tax remaining payable: VND 50,000,000 – VND 15,000,000 = VND 35,000,000.
The above example is only intended to illustrate how the 30% reduction is determined. The actual tax of each individual must be determined based on the tax calculation method, revenue, income and the tax laws applicable to each case.
How does the PIT reduction in Vietnam apply to 2026 and 2027?
A notable point is that the Resolution was issued on August 24, 2026, but the tax reduction policy applies to the tax periods of 2026 and 2027.
This means that, for individuals who satisfy the conditions, the tax reduction policy applies not only to the period from the effective date of the Resolution but also to the tax period of 2026 as provided for in the Resolution.
For 2027, the individual continues to determine the conditions for application on the basis of the revenue of 2027.
Can an individual in Vietnam with revenue of exactly VND 10,000,000,000 enjoy the reduction?
Under Resolution 43/2026/QH16, the condition is that revenue must “not exceed VND 10,000,000,000”.
This wording covers the case where revenue is exactly VND 10,000,000,000.
Therefore, in principle, an individual whose annual revenue is exactly VND 10,000,000,000 is not excluded from the policy merely because the revenue reaches the VND 10,000,000,000 threshold, provided that the other conditions under the Resolution are satisfied.
Conversely, where revenue exceeds VND 10,000,000,000, the revenue condition for applying the 30% reduction under the Resolution is not satisfied.
Determining revenue is therefore particularly important for business individuals in the course of determining their tax obligations.
Is all income of an individual in Vietnam eligible for the 30% PIT cut?
This is one of the points to note when studying the 2026 tax reduction policy.
Resolution 43/2026/QH16 provides for a tax reduction on income from business of resident individuals who satisfy the revenue condition.
Therefore, the policy should not be understood as granting an individual a 30% reduction of the entire amount of PIT arising from all sources of income.
For example, an individual who simultaneously has:
- Income from salaries and wages;
- Income from business activities;
- Other income subject to PIT.
In that case, the tax reduction under the Resolution must be determined within the scope of the income from business that falls within the prescribed scope, and the 30% reduction does not automatically apply to the individual’s entire PIT obligation.
How should a business individual in Vietnam determine revenue to apply the policy?
Revenue is an important criterion for determining whether an individual is eligible for the tax reduction.
For each year, a business individual should proactively review the revenue arising during the year to determine whether the threshold of not exceeding VND 10,000,000,000 is met.
The following basic steps may be taken:
- Step 1: Determine whether the individual is a beneficiary. First, determine whether the individual is a resident individual and has income from business.
- Step 2: Determine the revenue of the corresponding year. For the tax period of 2026, determine the annual revenue of 2026. For the tax period of 2027, determine the annual revenue of 2027.
- Step 3: Compare against the VND 10,000,000,000 threshold. If revenue does not exceed VND 10,000,000,000 and the other conditions are satisfied, the individual falls within the group to be considered for the tax reduction.
- Step 4: Determine the PIT payable. The individual determines the PIT payable in accordance with the tax laws corresponding to the business activities.
- Step 5: Determine the amount of tax reduced. In principle, the amount reduced is determined as: PIT payable × 30%.
- Step 6: Determine the tax remaining payable. PIT remaining payable after reduction: PIT payable – PIT reduced.
- During implementation, the individual must retain vouchers, books, invoices, documents evidencing revenue and other related records as prescribed in order to ensure a basis for determining tax obligations.
What does the 2026 tax reduction policy mean for business individuals in Vietnam?
The National Assembly’s decision to grant a 30% reduction of the PIT payable to business individuals with annual revenue not exceeding VND 10,000,000,000 is a direct support measure. This personal tax reduction targets the group of business individuals whose revenue is relatively small.
According to information from the National Assembly, the policy was designed to help remove difficulties and, together with other tax incentives, create conditions for the recovery and development of production and business for business households, business individuals and micro-enterprises.
For business individuals, the reduced tax may create additional resources to:
- Maintain business operations;
- Supplement working capital;
- Expand business scale;
- Invest further in machinery and equipment;
- Increase the ability to accumulate and reinvest;
- Reduce cost pressure in business operations.
The policy also reflects an orientation towards direct support: it seeks to reduce personal income tax actually payable rather than merely adjusting indirect factors of business operations.
What should business individuals in Vietnam note about the PIT reduction conditions?
- Correctly identify the beneficiaries: the policy focuses on resident individuals with income from business. Individuals therefore need to correctly determine their residency status and the source of income within the scope of application.
- Monitor revenue each year: the VND 10,000,000,000 revenue threshold is determined for each corresponding year. Individuals should not assume that satisfying the condition in 2026 automatically means satisfying the condition in 2027.
- The reduction is 30% of the tax payable: confusion between a 30% reduction of the tax payable and a 30% reduction of revenue or income must be avoided.
- It does not apply to all income of the individual: the Resolution provides for income from business, so individuals need to correctly determine the scope of income eligible for the policy.
- Retain complete records evidencing revenue: revenue is an important criterion for determining eligibility for the policy. Individuals should therefore proactively manage vouchers, invoices, books and documents relating to business activities, or use professional tax accounting services.
Frequently asked questions
By what percentage is the tax reduced in 2026?
Under Resolution 43/2026/QH16, resident individuals with income from business who satisfy the revenue condition are granted a 30% reduction of the PIT payable for the tax periods of 2026 and 2027.
Does the 2026 PIT reduction apply to salaries and wages?
The 2026 PIT reduction does not apply to salaries and wages under the reduction policy in Resolution 43/2026/QH16. This policy provides for a 30% reduction of the PIT payable on income from business of resident individuals who satisfy the revenue condition.
If an individual has revenue not exceeding VND 10,000,000,000 in 2026 but exceeding VND 10,000,000,000 in 2027, for which year is the PIT reduced?
Where a business individual has revenue in 2026 not exceeding VND 10,000,000,000 and satisfies the other conditions, the 30% reduction of the PIT payable applies to the tax period of 2026. If revenue in 2027 exceeds VND 10,000,000,000, the individual does not satisfy the revenue condition for applying the reduction policy to the tax period of 2027.
Thus, the revenue condition is considered for each corresponding tax period. Being eligible in 2026 does not give rise to a right to a tax reduction for 2027 if the individual no longer satisfies the conditions under Resolution 43/2026/QH16.
If a business individual has revenue not exceeding VND 10,000,000,000 but carries out multiple business activities, is the 30% reduction of PIT available?
In principle, Resolution 43/2026/QH16 provides for a 30% reduction of the PIT payable on income from business of resident individuals whose annual revenue does not exceed VND 10,000,000,000. Therefore, where an individual carries out multiple business activities, the revenue from the activities within the scope of application must be fully determined for comparison with the VND 10,000,000,000 threshold.
If the total revenue within the scope of application does not exceed VND 10,000,000,000 and the individual satisfies the other conditions under the Resolution, the 30% reduction of the PIT payable may be considered.
Individuals should aggregate and reconcile all revenue from business activities in full to avoid incorrectly determining eligibility for the tax reduction.
The personal income tax reduction in Vietnam 2026 is a practical support policy for business individuals who satisfy the conditions. The Tax Agent of Viet An Law Firm is always ready to advise and support clients on tax policies and tax laws, including tax accounting services, in accordance with regulations!