

Corporate tax finalisation services in Vietnam provided by Viet An Tax Agent support enterprises in preparing dossiers for corporate income tax finalisation and personal income tax (PIT) finalisation, determining the tax payable and handling issues arising before the dossiers are submitted. Tax finalisation is not merely the aggregation of year-end figures; it also requires the accurate determination of tax adjustments, deductible expenses, provisional tax paid and the basis for applying tax incentives.
Viet An Tax Agent provides year-end tax finalisation services for domestic enterprises and foreign-invested enterprises (FDI). Combining expertise in accounting, taxation and legal advice, Viet An helps clients prepare dossiers, minimise errors and fulfil their tax obligations in accordance with Vietnamese law.
Corporate tax finalisation services in Vietnam at Viet An
Tax finalisation is the determination of tax obligations for the finalisation period based on business results, taxable income, adjustments and the tax already paid in accordance with regulations.
Depending on the needs of each enterprise, Viet An Tax Agent provides the following service groups, which can be combined with our accounting and tax services for foreign-invested companies in Vietnam:
| Service | Scope of support |
| CIT finalisation | Determining taxable income, deductible expenses, incentives and tax payable |
| PIT finalisation | Aggregating income, tax withheld and the finalisation dossier of the income-paying organisation |
| Tax finalisation for FDI companies | Reviewing tax obligations related to cross-border transactions, related-party transactions and foreign employees |
| Support with tax explanation dossiers | Preparing documents, reconciling figures and supporting work with the tax authority under lawful authorisation |
Enterprises may engage tax finalisation services for one financial year, several outstanding periods or a specific tax type.
The preparation and submission of annual tax finalisation dossiers should be distinguished from tax inspections conducted by competent authorities. Enterprises proactively fulfil their declaration obligations as required, without waiting for the tax authority to issue an inspection decision.
Scope of Viet An Tax Agent’s tax finalisation services in Vietnam
Corporate income tax (CIT) finalisation services
For the CIT finalisation Vietnam’s regulations require, Viet An performs the following tasks within the scope of the contract:
- Reconciling accounting profit with taxable income;
- Determining revenue, other income and tax adjustments;
- Checking the conditions for recognising deductible expenses;
- Determining losses carried forward from previous periods;
- Checking the basis for applying tax incentives, exemptions and reductions;
- Reconciling the provisional CIT paid during the year;
- Determining additional tax payable or tax overpaid;
- Preparing the finalisation return and appendices as required;
- Supporting the submission of the dossier and handling related notices.
For enterprises with specific transactions, Viet An separately assesses items that may affect tax obligations before completing the CIT finalisation Vietnam’s tax regulations require.
Personal income tax finalisation services in Vietnam
For income-paying organisations, our services for the PIT finalisation Vietnam’s tax law requires include:
- Aggregating income from salaries and wages;
- Reconciling the PIT withheld;
- Checking deduction and dependant data;
- Identifying employees eligible to authorise the organisation to finalise their tax;
- Preparing the finalisation return and related appendices;
- Determining remaining tax payable or tax overpaid;
- Supporting dossier submission and explaining figures when necessary.
For employees who must finalise their tax directly, Viet An can provide separate advice upon request. In-depth information is available on our personal income tax finalisation services in Vietnam page.
Tax finalisation for FDI companies in Vietnam
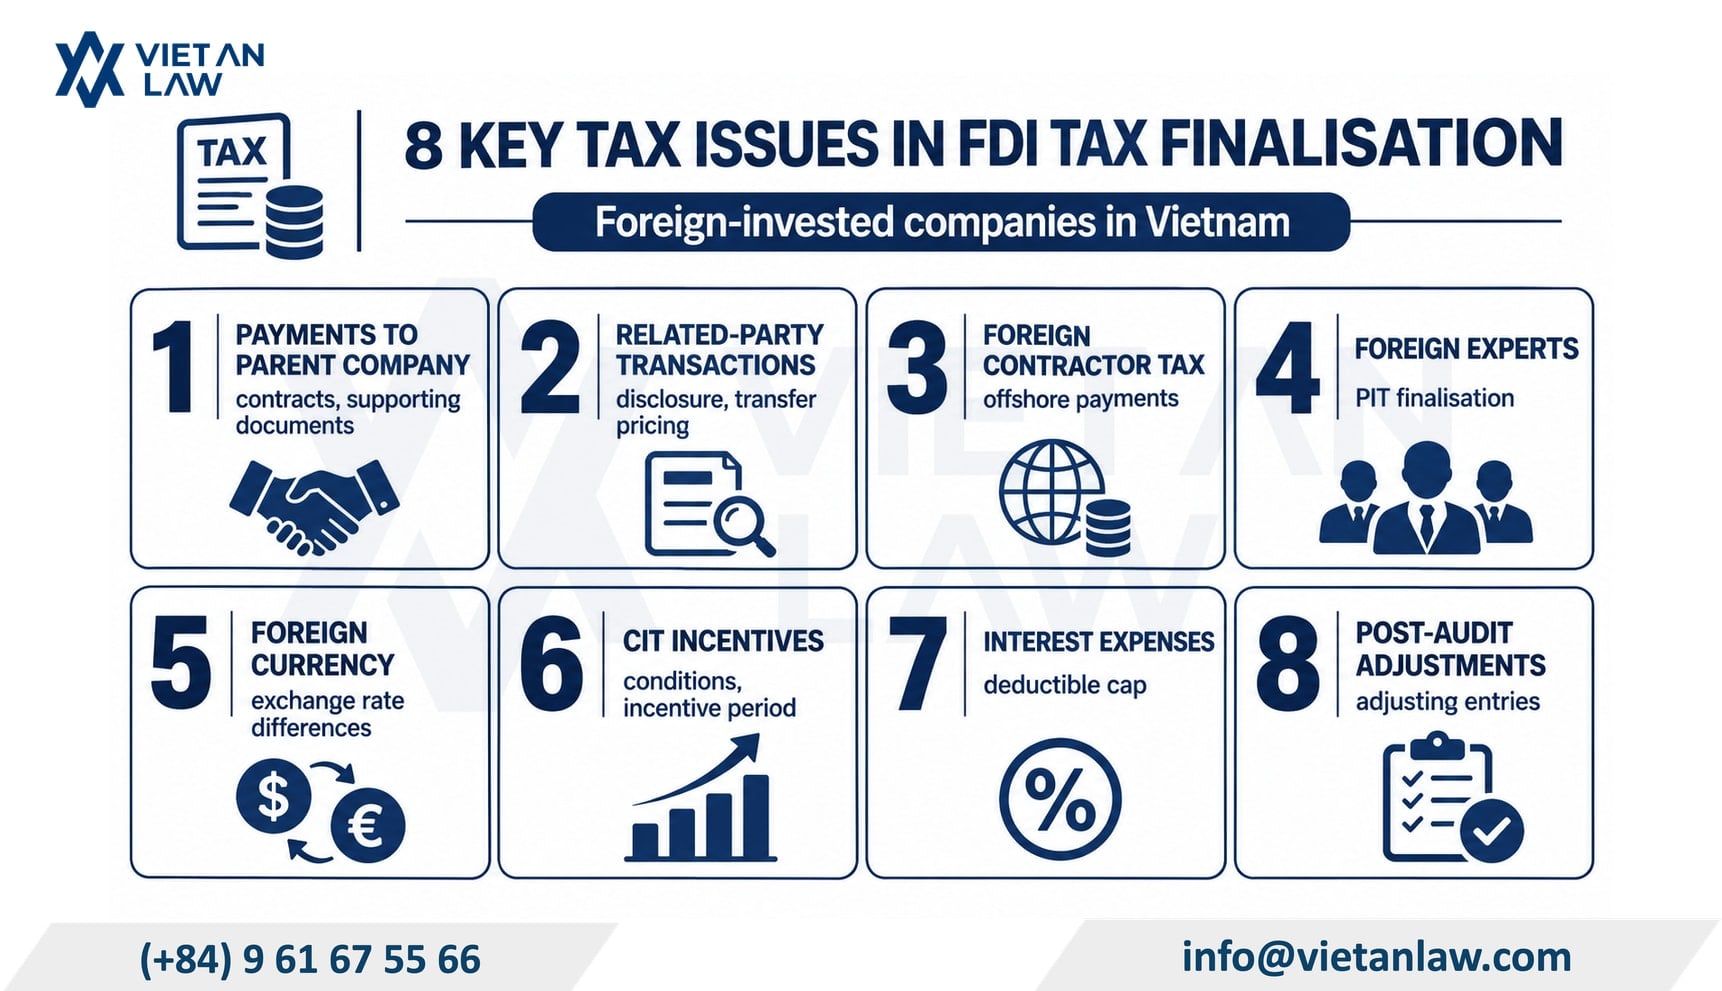
Viet An’s tax finalisation service for FDI enterprises helps foreign-invested enterprises Vietnam has licensed determine their CIT and PIT obligations and handle issues related to cross-border transactions.
In addition to ordinary finalisation requirements, FDI companies should pay attention to management fees paid to the parent company, related-party transactions, offshore payments subject to the foreign contractor tax Vietnam applies, income of foreign experts and the conditions for investment tax incentives.
Specific tax issues to check during finalisation
| Issue | Points to review |
| Expenses paid to the parent company | Nature of services, contracts, cost allocation basis and payment vouchers |
| Related-party transactions | Related-party relationships, declaration obligations, pricing and transfer pricing documentation |
| Foreign contractor tax | Tax obligations arising from payments to foreign organisations and individuals |
| Foreign experts | Income, allowances, taxable benefits and PIT finalisation obligations |
| Foreign currency transactions | Exchange rate differences affecting taxable income |
| CIT incentives | Conditions, incentive period and income eligible for incentives |
| Interest expenses | Deduction conditions and caps applicable to related-party transactions |
| Post-audit adjustments | Impact of adjusting entries on tax finalisation figures |
For the 2026 CIT period, enterprises with related-party transactions should review the transfer pricing compliance Vietnam’s Decree 255/2026/ND-CP requires; this decree takes effect from July 1, 2026 and applies from the 2026 CIT period.
Reviewing payments to the parent company and related parties
Management, consulting, royalty and technical service fees paid to an overseas parent company may significantly affect the taxable income of an FDI enterprise.
Viet An helps reconcile contracts, evidence of services actually rendered, pricing methods and payment vouchers to assess whether the expenses can be recognised upon tax finalisation.
Where an enterprise has related-party transactions, it is necessary to determine the declaration obligations, the preparation of transfer pricing documentation and the conditions for exemption from such documentation, if any.
PIT finalisation for foreign experts
For foreign employees, PIT obligations may involve income paid by multiple parties, including salaries, bonuses, housing allowances, tuition fees, insurance and other benefits.
Viet An helps determine finalisation obligations based on residency status, source of income, actual working time and relevant regulations.
Where cross-border income arises, enterprises should consider the provisions of double taxation avoidance agreements, if the conditions for application are met.
Coordinating audit and FDI tax finalisation dossiers
FDI enterprises are subject to mandatory annual audits of their financial statements under the law. However, audited financial statements do not replace the tax finalisation dossier.
Viet An helps reconcile post-audit adjustments, determine their impact on taxable income and complete the finalisation dossier in line with the adjusted figures.
Companies that need to outsource regular accounting and tax declaration work may refer to Viet An’s accounting and tax services for foreign-invested companies in Vietnam.
Tax finalisation risks enterprises in Vietnam should check before filing
Before preparing and submitting the tax finalisation dossier, enterprises need to identify items that may change the tax payable. Errors in the timing of revenue recognition, deductible expenses, loss carry-forwards or provisional tax payments may lead to dossier adjustments, supplementary payments and late payment interest.
Common risks in tax finalisation
| Situation | Risk to check |
| Accounting revenue differs from taxable revenue | Revenue recognised in the wrong period or adjustments not fully identified |
| Expenses lacking supporting documents | Expenses failing to meet the conditions for deduction when calculating CIT |
| Enterprise incurring losses for several years | Incorrect determination of the carry-forward period or amount of losses |
| Insufficient provisional CIT payments | Late payment interest may arise under regulations |
| Large interest expenses | Conditions and deduction caps not fully determined |
| Inconsistent payroll records | Discrepancies between salary expenses, taxable income and PIT withholding data |
| Application of tax incentives | Incorrect determination of eligible entities, timing or scope of incentives |
| Figures changed after audit | Impact of adjusting entries on the finalisation dossier not assessed |
For FDI enterprises, the specific transactions mentioned above should also be reviewed, particularly payments to related parties, the foreign contractor tax Vietnam imposes on offshore payments and the income of foreign experts.
Solutions before submitting the finalisation dossier
As part of corporate tax compliance, Viet An helps enterprises identify issues that directly affect the finalisation period, including:
- Reconciling accounting figures with tax returns and financial statements;
- Determining adjustments that increase or decrease taxable income;
- Checking provisional tax already paid and the remaining tax payable;
- Assessing supporting documents for risky items;
- Providing guidance on lawfully supplementing or adjusting dossiers before declaration.
Where an enterprise has several years of incomplete accounting records or needs a review of its entire accounting system, Viet An provides accounting records review services with a more in-depth scope.
Documents to prepare for tax finalisation services in Vietnam
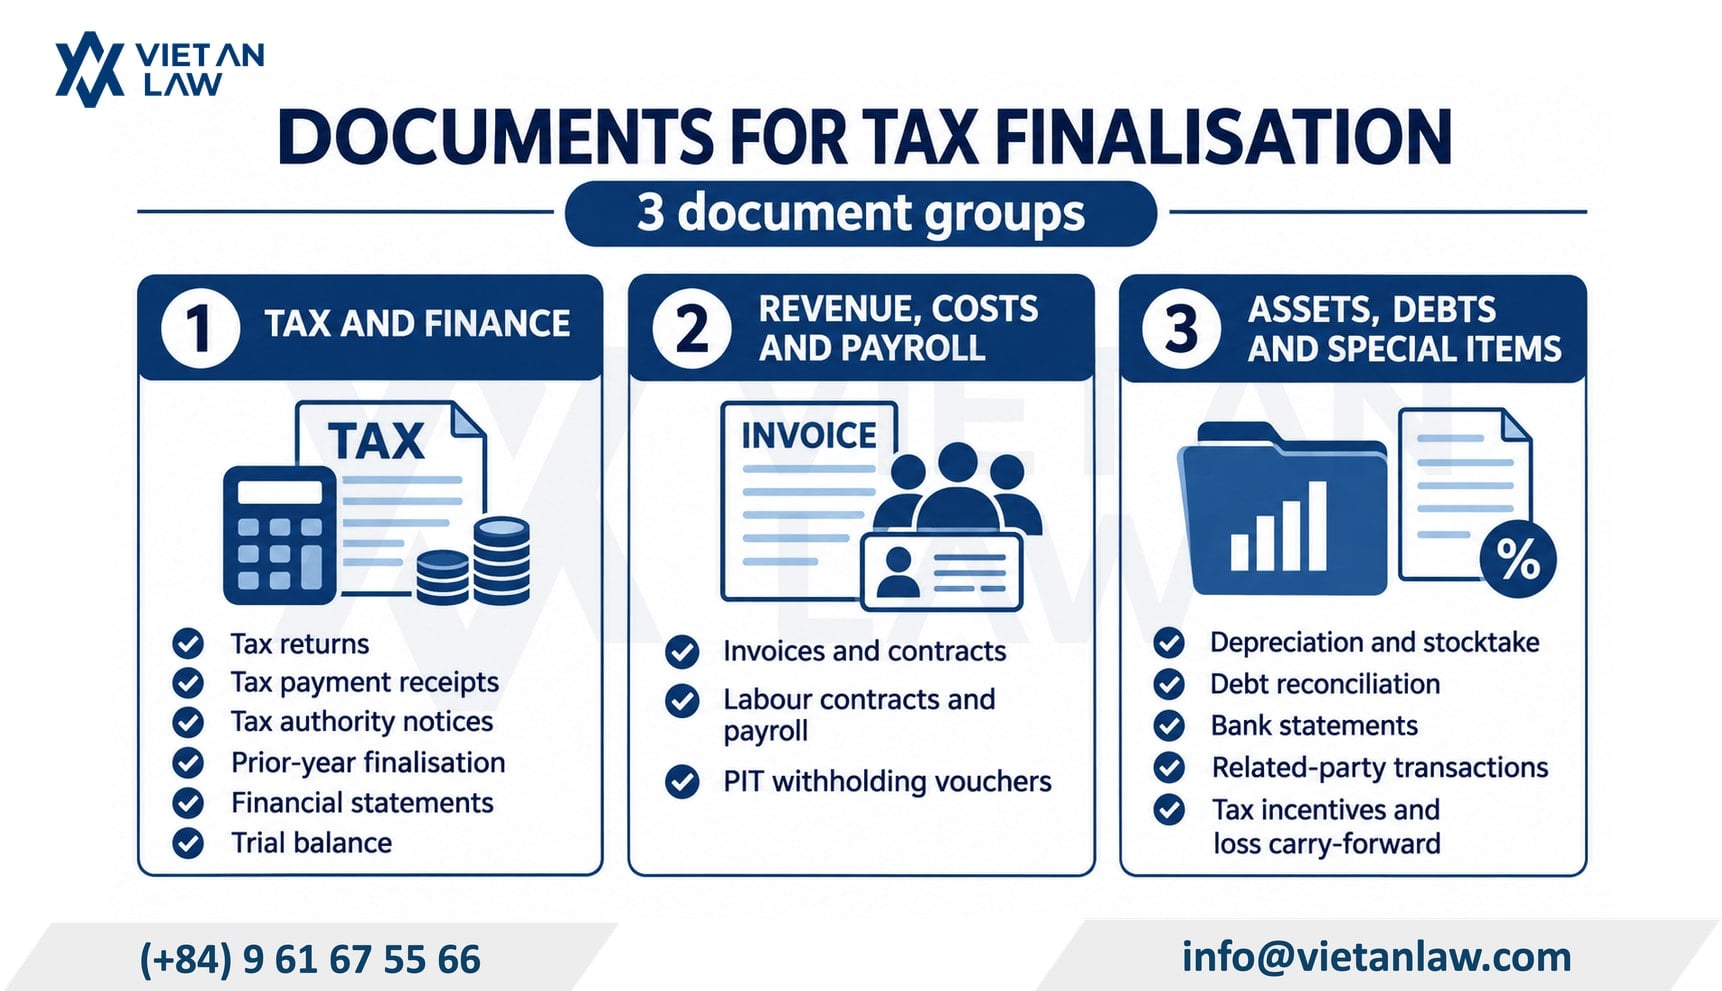
Depending on the tax type, business lines and actual situation, enterprises should prepare the following groups of documents:
| Document group | Documents |
| Tax records | Tax returns, tax payment vouchers, tax authority notices and finalisation dossiers of previous periods |
| Financial records | Financial statements, trial balance and related accounting data |
| Revenue and expenses | Invoices, contracts, payment vouchers, acceptance and handover records |
| Personnel records | Labour contracts, payroll, withholding vouchers and PIT finalisation authorisations |
| Assets and inventory | Depreciation data, cost allocation, stocktake and inventory movement records |
| Receivables and payables | Debt reconciliations, bank statements and payment vouchers |
| Special records | Documents on related-party transactions, tax incentives, loss carry-forwards and cross-border transactions, if any |
Viet An will conduct a preliminary review of the dossier and prepare a list of additional documents corresponding to the finalisation period, avoiding requests for irrelevant documents.
When should enterprises in Vietnam use tax finalisation services?
Enterprises may use the tax finalisation services Vietnam’s businesses rely on in the following cases:
- The financial year is about to end but the finalisation dossier has not been completed;
- Accounting figures and tax declaration figures need to be reconciled;
- Revenue, expenses or tax incentives arise that need to be determined separately;
- Accounting staff changed during the period;
- There are related-party transactions or cross-border payments;
- Finalisation dossiers for previous years need to be prepared or supplemented;
- A request for documents or explanations has been received from the tax authority.
Enterprises already using comprehensive accounting and tax services in Vietnam should check the scope of their current contract to determine whether finalisation work is included, avoiding duplicate costs.
Tax finalisation deadlines for enterprises in Vietnam
Enterprises need to determine the deadline for submitting the finalisation dossier based on the tax type, tax period and their legal status.
Under the applicable tax administration regulations, the deadline for submitting an enterprise’s annual tax finalisation dossier is generally the last day of the third month from the end of the tax year.
For example, for an enterprise whose financial year ends on December 31, 2026, the usual deadline for submitting the 2026 CIT finalisation dossier is March 31, 2027.
For income-paying organisations, the deadline for the PIT finalisation Vietnam’s regulations require is determined under the rules applicable to organisations.
In cases of dissolution, termination of operations, reorganisation or special tax periods, finalisation deadlines and obligations need to be considered separately.
Completing the dossier on time does not replace the obligation to pay the full amount of tax arising under the regulations.
Tax finalisation costs for enterprises in Vietnam
The cost of the tax finalisation services Vietnam’s enterprises use is determined based on the tax type, financial year, volume of documents and the completeness of the dossier.
| Criteria | Basis for determining costs |
| Scope of services | CIT finalisation, PIT finalisation or both |
| Number of finalisation periods | One or several financial years |
| Transaction volume | Number of vouchers, invoices and employees |
| Dossier status | Completed or requiring supplementation and adjustment |
| Specific transactions | Related-party transactions, tax incentives, cross-border transactions |
| Additional work | Supplementary declarations, explanation support or handling of old dossiers |
After reviewing the information, Viet An Tax Agent provides a quotation and clearly defines the work within the scope of the contract, so that tax finalisation costs are transparent from the outset.
Standard tax finalisation fees do not automatically include re-recording accounts for several years (which falls under comprehensive accounting and tax services in Vietnam), auditing financial statements, handling tax disputes or representing the enterprise before competent authorities beyond the agreed scope.
Tax finalisation procedures at Viet An Tax Agent in Vietnam
Step 1: Receiving information
The enterprise provides its tax code, business lines, finalisation period, tax types and dossier status.
Step 2: Assessing the dossier and providing a quotation
Viet An determines the workload, the documents to be supplemented and the scope of services before the contract is agreed.
Step 3: Carrying out tax finalisation
Reconciling relevant figures, determining tax obligations, and preparing the finalisation return and applicable appendices.
Step 4: Submitting the dossier
Supporting electronic submission of the tax finalisation dossier, monitoring acknowledgement notices and handling supplementation requests within the scope of authorisation, so that the tax finalisation procedures are completed in full.
Step 5: Handover and post-finalisation support
Handing over the dossier, results and information on remaining tax obligations, while guiding the enterprise on archiving documents for tax administration purposes.
Explanation support when the tax authority in Vietnam reviews finalisation dossiers
When the tax authority requests explanations or documents, enterprises need to identify the content, tax period and scope of the requested documents.
Viet An Tax Agent can provide the tax audit support Vietnam’s enterprises often need: compiling documents, explaining figures, preparing written explanations and working with the tax authority within the scope of lawful authorisation.
Where supplementary declarations, adjustments to tax obligations or decisions on handling violations arise, Viet An advises on suitable solutions based on the actual dossier and legal regulations.
Explanation support services do not constitute a commitment that the tax authority will accept all figures or that the enterprise will not incur additional tax.
Why choose Viet An’s tax finalisation services in Vietnam?
Viet An Tax Agent provides tax finalisation services that combine the preparation of tax dossiers with a review of the legal basis of transactions affecting financial obligations, supporting both corporate tax compliance and year-end tax finalisation.
- Advice by tax type: The scope of work is determined according to the tax type and finalisation period.
- Support for domestic and FDI enterprises: Reviewing obligations arising from business activities and cross-border transactions of foreign-invested enterprises Vietnam hosts.
- Dossier control before declaration: Notifying items that need to be adjusted or supplemented with supporting evidence.
- Transparent costs: Quotations based on workload and dossier status.
- Professional support after submission: Coordinating explanations of matters related to the dossiers handled under the contract.
Frequently asked questions about tax finalisation services
Does a loss-making enterprise have to finalise corporate income tax?
Incurring losses does not automatically exempt an enterprise from the obligation of corporate income tax finalisation. The preparation of the dossier depends on the operating status and the exemption cases provided by law. Losses are determined and tracked for carry-forward to subsequent periods when the conditions are met.
Is the yearly tax finalisation a tax inspection?
No. Yearly tax finalisation is an obligation of the taxpayer. A tax inspection is a separate activity of the competent authority and is conducted in accordance with legal procedures.
Can tax finalisation be outsourced for previous years?
Yes. Viet An can receive dossiers from previous years to assess outstanding obligations, errors and conditions for supplementary declarations. The scope of handling depends on the dossier status and any decisions already issued by competent authorities.
Are FDI enterprises required to prepare transfer pricing documentation?
Not all FDI enterprises are required to prepare transfer pricing documentation. The obligation depends on whether related-party relationships and transactions arise and on the exemption conditions under the applicable regulations, which is a key point of the transfer pricing compliance Vietnam’s tax authorities review.
What should an enterprise do if it discovers errors after submitting the finalisation dossier?
The enterprise needs to identify the erroneous items, their impact on tax obligations and the conditions for supplementary declarations under the tax administration law. Viet An supports the review and preparation of adjustment dossiers within the scope of services and provides the tax audit support Vietnam’s enterprises may need if the tax authority later reviews the dossier.
Contact Viet An for corporate tax finalisation in Vietnam
Timely tax finalisation with full supporting evidence and accurate determination of tax obligations helps enterprises minimise legal risks, proactively manage finances and work smoothly with the tax authority.
Viet An Tax Agent provides corporate tax finalisation services in Vietnam for domestic and FDI enterprises, supporting the preparation of CIT and PIT finalisation dossiers, the review of related tax obligations and explanations within the scope of services.
Clients who need end-of-year tax finalisation, handling of dossiers for previous periods or advice on corporate tax obligations may contact Viet An Law Firm – Hotline: 0961 571 818 for advice and a quotation.
Written by: Tax specialist: Nguyen Thi Thuy Trang
Reviewed by: Tax specialist Nguyen Thi Ngoc Diep
Hotline | Zalo | WhatsApp: (+84) 961 571 818
Email: info@vietanlaw.com
Hanoi office: 3rd Floor, Hoang Ngan Plaza Building, 125 Hoang Ngan Street,
Yen Hoa Ward, Hanoi
Ho Chi Minh City office: Room 2.26–2.27, Charmington La Pointe Building, 181 Cao Thang Street, Hoa Hung Ward, Ho Chi Minh City.