

Entering 2026, as the new provisions of the Law on Social Insurance 2024 and its implementing documents are applied consistently, even a small error in determining the time of participation or the method of calculating the average salary can significantly change the benefit an employee receives. Mastering how to calculate lump-sum social insurance benefits in Vietnam in 2026 not only helps employees proactively plan their personal finances but also provides an important legal basis for protecting their lawful rights when the employment relationship ends. In the article below, Viet An Law Firm analyses the current legal provisions in detail so that clients can look them up and apply them accurately.
Eligibility for lump-sum social insurance benefits in 2026 under Vietnam law
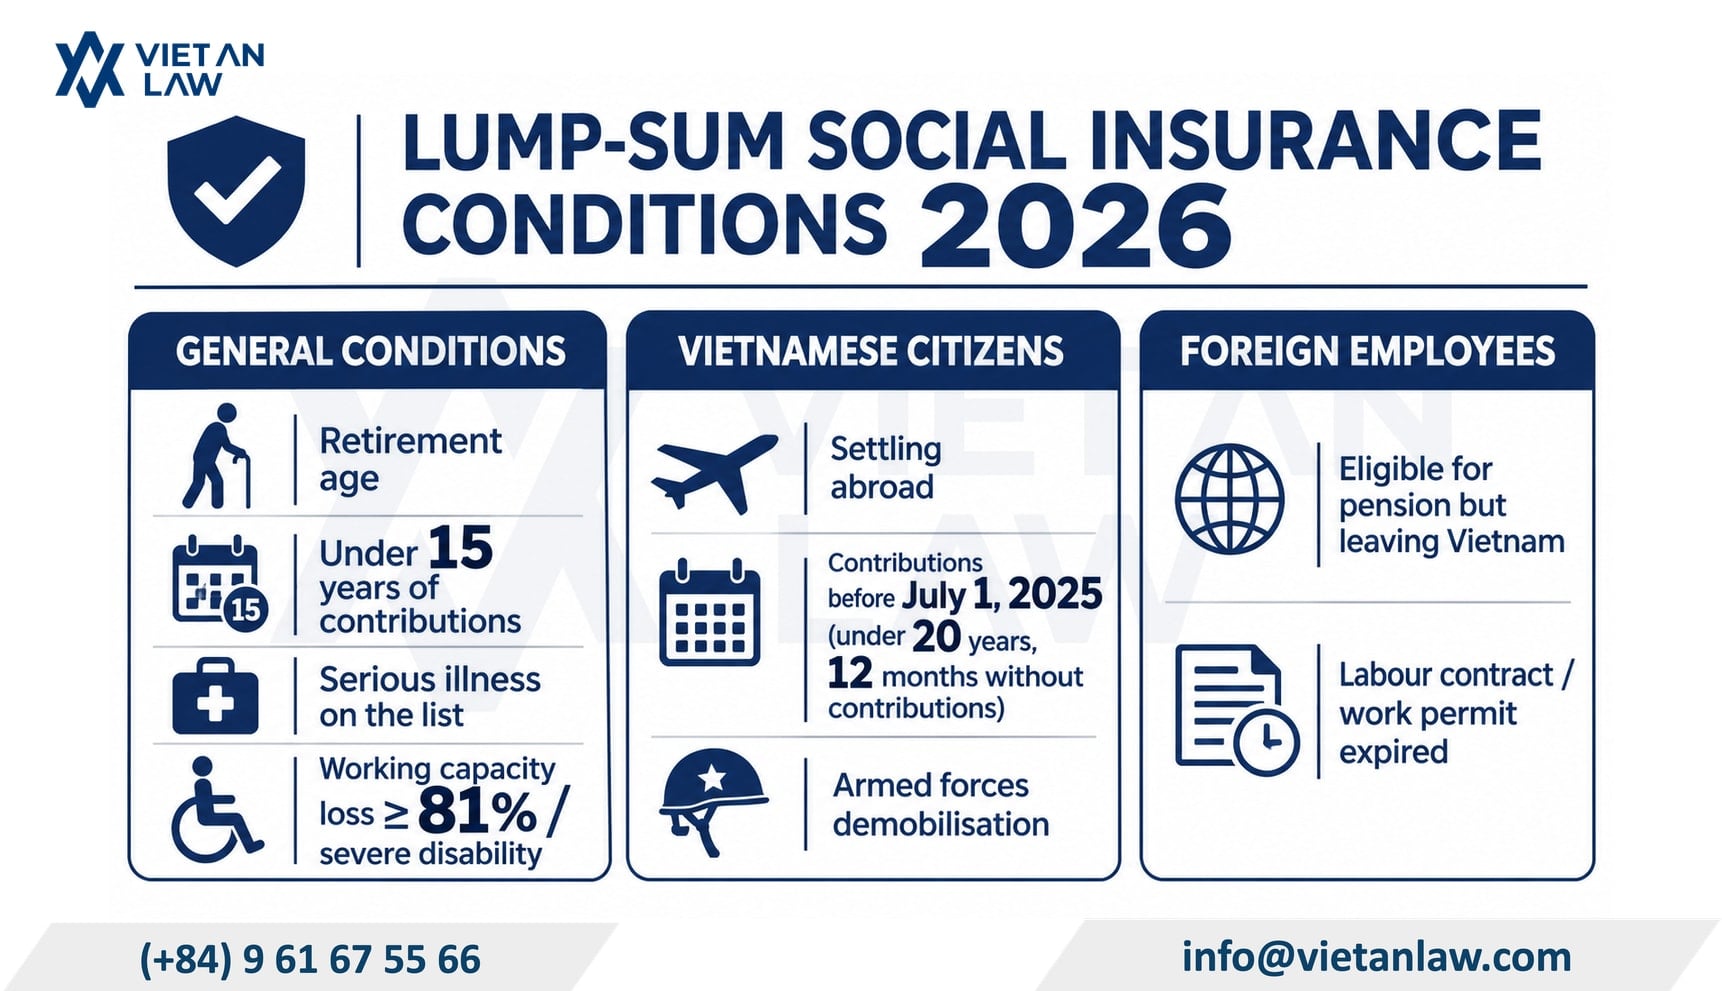
Pursuant to Articles 70 and 102 of the Law on Social Insurance 2024 and Article 14 of Decree No. 158/2025/ND-CP, after ceasing social insurance participation and submitting a request, clients are entitled to a lump-sum social insurance benefit if they meet the general conditions or the specific conditions below:
General conditions applicable to all social insurance participants
Employees who are Vietnamese citizens (participating in compulsory or voluntary social insurance) and foreign employees working in Vietnam are entitled to a lump-sum social insurance benefit if they fall into one of the following 03 cases:
- Having reached the statutory retirement age but having less than 15 years of social insurance contributions. For Vietnamese citizens, those who do not take the lump-sum benefit may choose to receive a monthly allowance.
- Suffering from one of the following dangerous diseases: cancer, poliomyelitis, decompensated cirrhosis, severe tuberculosis or AIDS.
- Having a working capacity reduction of 81% or more, or being a person with an extremely severe disability.
Specific conditions for each group of participants
In addition to the 03 general cases above, the law provides further cases in which a lump-sum social insurance benefit is granted to specific groups as follows:
- For employees who are Vietnamese citizens (participating in compulsory or voluntary social insurance):
- Going abroad to settle legally.
- Having social insurance contributions before July 1, 2025, with less than 20 years of contributions, and not participating in either compulsory or voluntary social insurance for 12 months. This condition is determined specifically as follows:
- At the time of settlement, the employee still has social insurance contribution periods before July 1, 2025 to be counted for benefits.
- Having 12 consecutive months without social insurance contributions up to the month preceding the month in which the social insurance agency receives the dossier, and not participating in compulsory or voluntary social insurance at the time of submitting the dossier.
- Employees in the armed forces, cipher services or standing militia (participating in compulsory social insurance) who are demobilised, discharged or quit their jobs without participating in compulsory or voluntary social insurance and are not eligible for a pension.
- For foreign employees working in Vietnam (participating in compulsory social insurance):
- Being eligible for a pension under the regulations but no longer residing in Vietnam.
- Their labour contract has been terminated, or their work permit, practising certificate or practising licence has expired without being renewed.
How to calculate lump-sum social insurance benefits in Vietnam in 2026 accurately
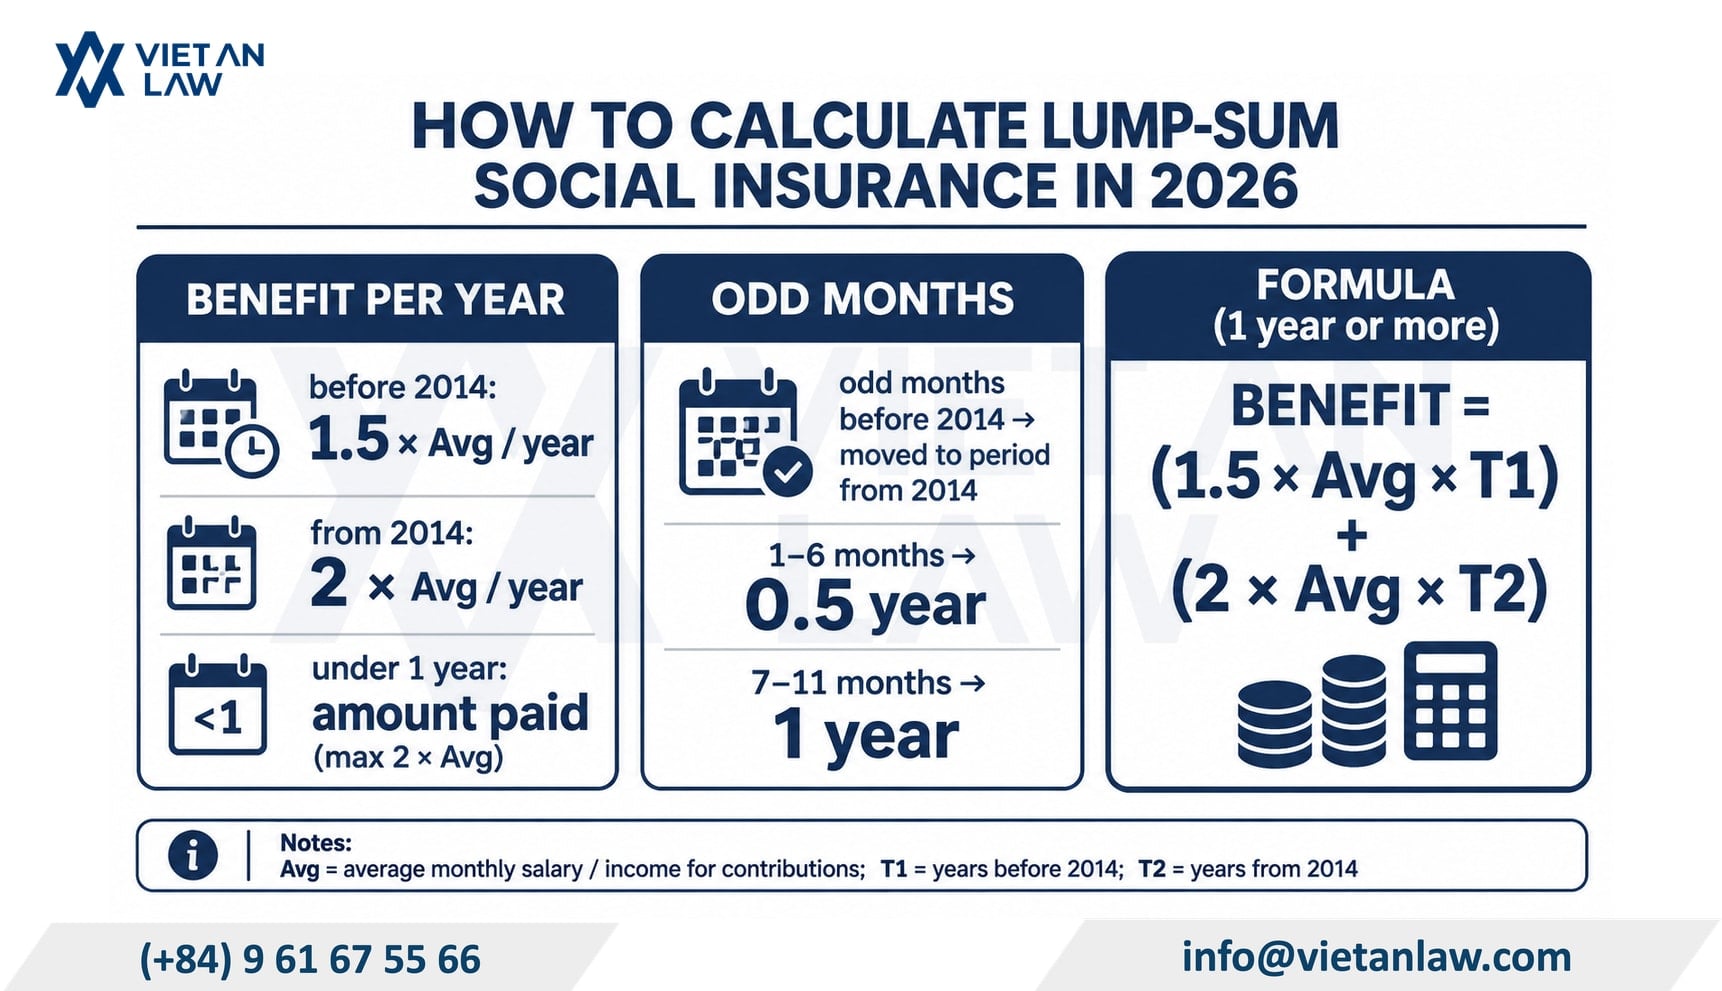
Once the eligibility for lump-sum social insurance benefits is established, the employee’s lump-sum benefit is determined based on the total number of years of contributions and the social insurance contribution basis under Articles 70 and 102 of the Law on Social Insurance 2024 and Article 17 of Decree No. 158/2025/ND-CP.
Benefit rates for lump-sum social insurance by contribution period
Pursuant to Clause 3, Article 70 of the Law on Social Insurance 2024 (for compulsory social insurance) and Clause 2, Article 102 of the Law on Social Insurance 2024 (for voluntary social insurance), the benefit for each year of social insurance contributions is divided around the 2014 milestone as follows:
- Contribution period before 2014: Each year of social insurance contributions is calculated as 1.5 months of the average monthly salary used as the basis for social insurance contributions, or 1.5 times the average monthly income used as the basis for social insurance contributions.
- Contribution period from 2014 onwards: Each year of social insurance contributions is calculated as 02 months of the average monthly salary used as the basis for social insurance contributions, or 02 times the average monthly income used as the basis for social insurance contributions.
- Where the contribution period is less than 01 year (under 12 months): The benefit equals the actual amount contributed to the social insurance fund, but not exceeding 02 months of the average monthly salary used as the basis for social insurance contributions, or 02 times the average monthly income used as the basis for social insurance contributions.
Converting social insurance contribution periods with odd months
When applying the 2026 calculation method for lump-sum benefits, the handling of odd months plays a decisive role in the number of years counted for clients’ benefits:
- Rule for transferring odd months before 2014: Under Point a, Clause 3, Article 70 and Point a, Clause 2, Article 102 of the Law on Social Insurance 2024, where an employee has social insurance contribution periods both before and after 2014 and the period before 2014 contains odd months, all such odd months are transferred to the contribution period from 2014 onwards for benefit calculation (multiplied by 2 months/year instead of 1.5 months/year).
- Rule for rounding odd months when calculating the total benefit period: Under Clause 6, Article 5 of the Law on Social Insurance 2024, when calculating social insurance benefits where the contribution period includes odd months, the calculation is as follows:
- 01 to 06 odd months are counted as half a year (0.5 year);
- 07 to 11 odd months are counted as one year (01 year).
Lump-sum social insurance formula and rules on State support
Based on Clauses 3 and 4, Article 70, and Clauses 2 and 3, Article 102 of the Law on Social Insurance 2024, the formula for calculating lump-sum social insurance for contribution periods of 01 full year or more is as follows:
Where:
- : Average monthly salary or income used as the basis for social insurance contributions, adjusted as prescribed.
- : Number of years of social insurance contributions before 2014 (after odd months have been transferred to the period from 2014 onwards).
- : Number of years of social insurance contributions from 2014 onwards (including odd months transferred from the period before 2014 and rounded as described above).
How to calculate the average salary for social insurance contributions and salary adjustment in Vietnam
Pursuant to Clause 7, Article 15 of Decree No. 158/2025/ND-CP, the average salary used as the basis for social insurance contributions serves as the basis for calculating lump-sum social insurance benefits, specifically for each group:
- For employees whose entire contribution period is under the salary regime decided by the employer: The average salary used as the basis for social insurance contributions is calculated over the entire contribution period.
- For employees whose entire contribution period is under the salary regime prescribed by the State: The average salary used as the contribution basis is calculated over the last years before stopping contributions or leaving work, depending on when they started participating in social insurance, under Clause 1, Article 72 of the Law on Social Insurance 2024. Specifically:
- Before January 1, 1995: the last 05 years;
- From January 1, 1995 to December 31, 2000: the last 06 years;
- From January 1, 2001 to December 31, 2006: the last 08 years;
- From January 1, 2007 to December 31, 2015: the last 10 years;
- From January 1, 2016 to December 31, 2019: the last 15 years;
- From January 1, 2020 to December 31, 2024: the last 20 years; from January 1, 2025 onwards: the entire contribution period.
Note: Where the employee’s contribution period is shorter than the number of years prescribed in Clause 1, Article 72 of the Law on Social Insurance 2024, the average salary of the months contributed is used.
- For employees with contribution periods under both the salary regime prescribed by the State and the salary regime decided by the employer: The common average salary used as the contribution basis is calculated across all periods, in which the periods under the State salary regime are averaged in accordance with Clause 1, Article 72 of the Law on Social Insurance 2024.
- For persons participating only in voluntary social insurance: The average income used as the contribution basis is the average of all incomes used as the basis for social insurance contributions over the entire contribution period.
- For persons with both voluntary and compulsory social insurance contribution periods: The average income and salary used as the basis for social insurance contributions is calculated as the total of the incomes used as the basis for voluntary social insurance contributions (adjusted) plus the average salary used as the basis for compulsory social insurance contributions multiplied by the total number of months of compulsory contributions, divided by the total number of months of voluntary and compulsory social insurance contributions.
Comparison of lump-sum social insurance rules between participant groups in Vietnam
To help clients easily compare when calculating lump-sum social insurance benefits in 2026, Viet An Law Firm has compiled the following comparison of legal criteria between compulsory and voluntary social insurance:
| Criteria | Compulsory social insurance | Voluntary social insurance |
| Benefit for each year of contributions before 2014 | 1.5 months of the average monthly salary used as the basis for social insurance contributions | 1.5 times the average monthly income used as the basis for social insurance contributions |
| Benefit for each year of contributions from 2014 onwards | 02 months of the average monthly salary used as the basis for social insurance contributions | 02 times the average monthly income used as the basis for social insurance contributions |
| Benefit for contributions of less than 01 year | The amount contributed, but not exceeding 02 months of the average monthly salary used as the basis for social insurance contributions | The amount contributed, but not exceeding 02 times the average monthly income used as the basis for social insurance contributions |
| Calculation of the average used as the benefit basis | Based on the last years (under the State salary regime) or the entire contribution period (under the salary regime decided by the employer) | The average of all incomes used as the basis for social insurance contributions over the entire contribution period |
| Deduction of State budget support for contributions | No State budget support arises for compulsory social insurance contributions | Excludes the State budget support for contributions, except for employees suffering from cancer, poliomyelitis, decompensated cirrhosis, severe tuberculosis or AIDS, or with a working capacity reduction of 81% or more or an extremely severe disability |
Dossier and procedures for claiming lump-sum social insurance in Vietnam in 2026
In addition to determining the lump-sum benefit, employees need to prepare a complete dossier and follow the correct procedures so that the social insurance agency can process the payment on time. Employees who prefer professional assistance can use lump-sum social insurance withdrawal services in Vietnam.
Components of the dossier for lump-sum social insurance
Under Articles 78 and 106 of the Law on Social Insurance 2024, the dossier for lump-sum social insurance includes:
- Social insurance book (electronic or paper version).
- The employee’s written request for the lump-sum social insurance benefit.
- For persons going abroad to settle: a certification by a competent authority of renunciation of Vietnamese nationality, or a notarised or certified Vietnamese translation of one of the documents proving settlement abroad, such as a passport, visa or permanent residence card, etc.
- For persons suffering from cancer, poliomyelitis, decompensated cirrhosis, severe tuberculosis or AIDS: a summary of the medical record, or the original or a copy of the hospital discharge certificate.
- For persons with a working capacity reduction of 81% or more or an extremely severe disability: the record of assessment of working capacity reduction issued by the Medical Assessment Council, or a copy of the certificate of extremely severe disability.
Procedures and time limit for settling lump-sum social insurance
- Settlement time limit: within 07 working days from the date of receiving a complete dossier as prescribed, the social insurance agency shall settle the claim; in case of refusal, it must respond in writing stating the reasons.
- Payment methods:
- Via a personal account opened at a commercial bank or a foreign bank branch in Vietnam;
- Or directly from the social insurance agency or an authorised service organisation, or through the employer.
Frequently asked questions about calculating lump-sum social insurance in 2026
If an employee started participating in social insurance after July 1, 2025, can they receive lump-sum social insurance in 2026 after 12 months of leaving work?
Under Point dd, Clause 1, Article 70 and Point dd, Clause 1, Article 102 of the Law on Social Insurance 2024, the condition for receiving lump-sum social insurance after 12 months of leaving work (with less than 20 years of contributions) only applies to employees who have social insurance contributions before July 1, 2025.
After receiving lump-sum social insurance in 2026, if the employee returns to work and continues to pay social insurance, will the previous contribution period be accumulated?
Pursuant to the second paragraph of Clause 3, Article 5 of the Law on Social Insurance 2024, contribution periods for which a lump-sum benefit has been paid are not counted towards the period used to calculate future social insurance benefits. When clients return to work and participate in social insurance, their contribution period is counted anew from the date contributions resume.
If an employee is eligible for both a monthly pension and a lump-sum benefit (e.g. settling abroad or suffering from cancer), how is the case handled?
Pursuant to Clause 6, Article 70 and Clause 5, Article 102 of the Law on Social Insurance 2024, an employee who is eligible for both a pension and a lump-sum social insurance benefit may freely choose to receive a monthly pension or a lump-sum benefit by submitting a written request to the social insurance agency.
If an employee has contributed for a total of 05 years and 08 months (from January 2020 to the end of August 2025), how many years are counted for lump-sum social insurance?
Pursuant to Clause 6, Article 5 of the Law on Social Insurance 2024, when calculating social insurance benefits, odd months from 07 to 11 are rounded up to 01 year. Therefore, the employee’s contribution period of 05 years and 08 months from 2020 to 2025 is rounded to 06 years of contributions from 2014 onwards, corresponding to a benefit of 6 years × 2 = 12 months of the average monthly salary used as the basis for social insurance contributions.
If a company went bankrupt or became unable to pay social insurance before July 1, 2024 and the employee has already received a lump-sum benefit for the period the company paid, how is the unpaid period handled?
Pursuant to Clause 1, Article 27 and Point b, Clause 2, Article 30 of Decree No. 158/2025/ND-CP, where the employer became unable to pay social insurance before July 1, 2024 and the employee had already received a lump-sum benefit, when the social insurance agency later confirms the additional late-paid or evaded contribution periods, the lump-sum benefit already received will not be readjusted; instead, the additionally confirmed contribution period will be reserved for the employee.
Above is Viet An Law Firm’s complete legal analysis of how to calculate lump-sum social insurance benefits in Vietnam in 2026. If clients need advice or wish to use lump-sum social insurance withdrawal services in Vietnam, please contact Viet An Law Firm for timely support.