

Termination of outbound investment projects in Vietnam is a compulsory legal procedure that investors must execute when offshore business operations conclude. This process involves liquidating assets, recovering capital, and remitting all legitimate income back to Vietnam. In 2026, the regulatory framework governing outward direct investment underwent significant revisions with the enactment of Decree 103/2026/ND-CP (effective April 3, 2026), replacing former regulations. Furthermore, Circular 38/2026/TT-BTC and Circular 34/2026/TT-NHNN have introduced updated guidance on standard reporting forms, statutory procedures, and foreign exchange management requirements. In this article, Viet An Law provides a comprehensive guide to help investors navigate the updated compliance roadmap for terminating offshore investment projects effectively.
When must an outbound investment in Vietnam project be terminated?
Pursuant to Article 28 of Decree 103/2026/ND-CP, an outward investment project shall terminate its operations in the following cases:
- The investor decides to terminate the project’s operations;
- The project’s operational term expires in accordance with the laws of the host country;
- Termination conditions specified in the contract or the enterprise’s charter are met;
- The investor transfers their entire overseas investment capital to a foreign investor;
- More than 24 months have elapsed since the issuance of the Outward Investment Registration Certificate or the confirmation of foreign exchange transaction registration, yet the investor has failed to implement – or is unable to implement – the project according to the registered schedule and has not carried out procedures to adjust said schedule;
- The overseas economic organization is dissolved or declared bankrupt in accordance with the laws of the host country;
- Pursuant to a court judgment or decision, or an arbitral award.
Thus, the termination of a project may stem from the investor’s proactive decision or from other objective or legal conditions necessitating the project’s conclusion.
What must the investor do after closing an outward investment project?
Immediately upon the termination of the project, the investor must liquidate the project in accordance with the laws of the host country or territory.
This is a crucial step prior to finalizing procedures in Vietnam.
The liquidation process may include:
- Liquidating project assets;
- Recovering outstanding receivables;
- Settling obligations to employees;
- Settling tax liabilities and other financial obligations abroad;
- Settling other payables;
- Recovering investment capital;
- Determining remaining profits and lawful income;
- Completing procedures for the dissolution or termination of the legal entity or project in the host country, if applicable.
Upon completion, the investor must obtain written confirmation or legal documentation evidencing the project’s termination and liquidation for use in the dossier to be submitted in Vietnam.
What is the time limit for remitting capital and income from project liquidation to Vietnam?
- Pursuant to Article 28 of Decree 103/2026/NĐ-CP, within 12 months from the date of the tax finalization report – or a document of equivalent legal validity under the laws of the host country regarding the completion of project liquidation – the investor must repatriate all proceeds from the project liquidation in accordance with foreign exchange management laws and relevant regulations.
- The sequence of events can be understood as follows: Project termination → Project liquidation abroad → Completion of tax finalization (or equivalent documentation) → Repatriation of all liquidation proceeds to Vietnam within 12 months → Completion of procedures in Vietnam within 60 days.
- Therefore, investors should not assume that the mere issuance of a project termination decision allows for the immediate closure of the investment file in Vietnam. The liquidation and repatriation of funds to Vietnam constitute a crucial part of the termination process.
Procedures for termination of outbound investment projects in Vietnam
Under the new regulations, within 60 days from the date of completing the liquidation of an overseas project and repatriating all proceeds from such liquidation (if any), the investor must carry out the corresponding procedures in Vietnam.
Case 1: Projects subject to the issuance of an outward investment registration certificate
The investor carries out procedures for termination of outward investment registration certificate.
Case 2: Projects not subject to the issuance of an outward investment registration certificate
The investor shall provide written notification of the termination of investment activities to the State Bank of Vietnam and the Ministry of Finance, while also committing to having completed the liquidation and repatriated any proceeds derived therefrom.
Dossier for terminating outbound investment in Vietnam projects
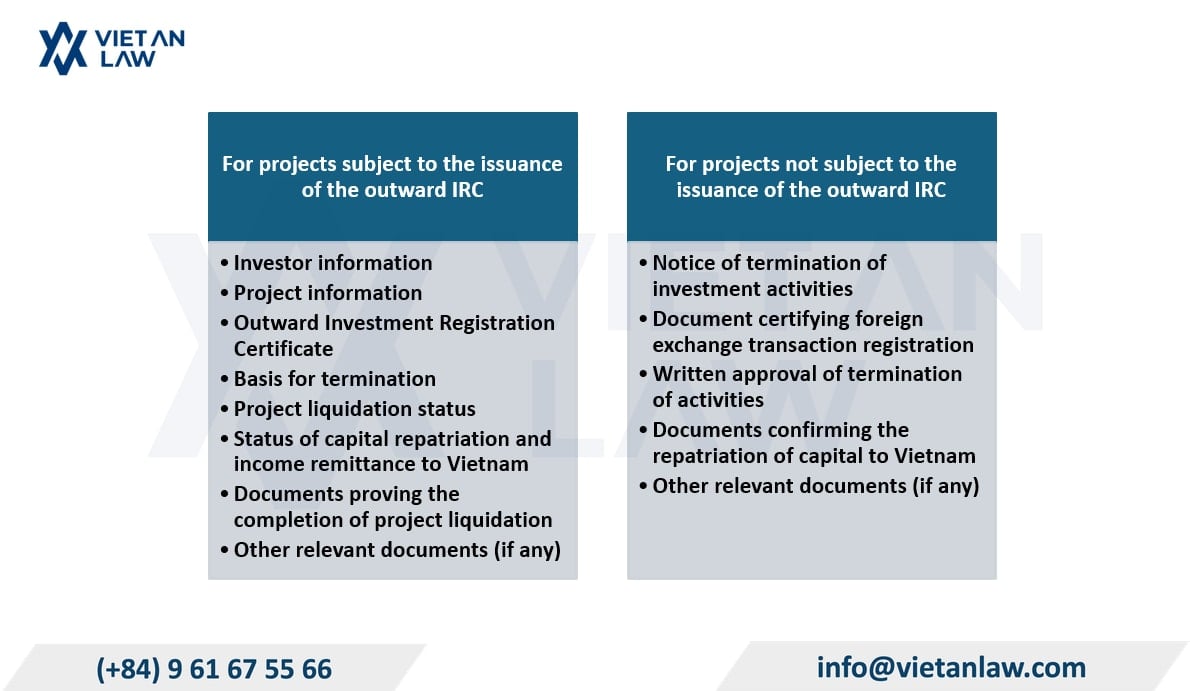
For projects subject to the issuance of the outward IRC
Investors must prepare the dossier for the termination of outward investment registration certificate in accordance with Decree 103/2006/ND-CP and current prescribed forms.
In essence, the dossier must demonstrate the following:
- Investor information
- Project information
- Outward Investment Registration Certificate
- Basis for termination
- Project liquidation status
- Status of capital repatriation and income remittance to Vietnam
- Documents proving the completion of project liquidation
- Other relevant documents (if any)
For projects not subject to the issuance of the outward IRC
The notification dossier must include supporting documents:
- Notice of termination of outward investment activities (Form I.21 issued with Circular 38/2026/TT-BTC);
- Document certifying foreign exchange transaction registration;
- Approval for the termination of operations from the host country or a document of equivalent legal validity;
- Document confirming the repatriation of capital to Vietnam;
- Other relevant documents, if any.
Remittance of investment capital and foreign income back to Vietnam
Upon the termination of a project, an investor may need to repatriate various funds to Vietnam, such as:
- Remaining investment capital;
- Proceeds from asset liquidation;
- Proceeds from capital transfer;
- Undistributed profits;
- Other lawful income derived from investment activities.
Under Circular 34/2026/TT-NHNN, the outward investment capital account is used to conduct receipt and payment transactions related to outward investment activities. Specifically, receipts include repatriated profits and lawful income, as well as capital returned to Vietnam in cases of capital recovery, transfer, reduction, liquidation, or termination of the overseas investment activity.
Therefore, enterprises must retain complete banking documentation regarding these fund transfers to support:
- Project termination documentation;
- Investment reporting;
- Foreign exchange management;
- Tax compliance;
- Explanations to state authorities when required.
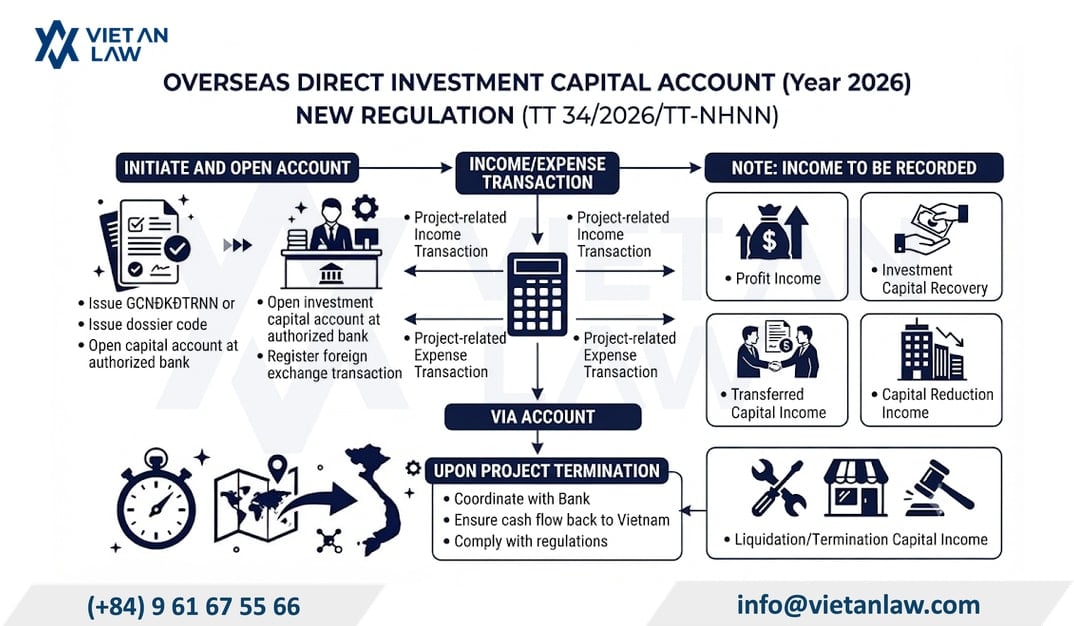
Circular 34/2026/TT-NHNN, issued on June 30, 2026, and effective from July 31, 2026, is a key document to consult when carrying out procedures to terminate an investment project and repatriate capital to Vietnam.
Under the new regulations, upon receiving the Overseas Investment Registration Certificate or an automated filing code (for projects not subject to the certificate requirement), investors must open an investment capital account at an authorized bank and implement foreign exchange transaction registration in accordance with regulations.
All receipts and payments related to overseas investment activities must be conducted through the investment capital account as prescribed.
Notably, the investment capital account may record:
- Receipt of profits and other lawful income repatriated from abroad;
- Recovery of investment capital;
- Receipt of capital from the transfer of overseas capital;
- Receipt of capital resulting from a capital reduction;
- Receipt of capital from the liquidation or termination of overseas investment activities.
Therefore, upon project termination, investors should coordinate with the bank holding their investment capital account to ensure that the repatriation of funds from abroad to Vietnam is executed in compliance with regulations.
Key considerations when seeking to end outward investment activities in Vietnam
- Firstly, the liquidation process abroad must be completed before finalizing the termination procedures in Vietnam. Investors must possess legal documentation proving that the project has been terminated and liquidated.
- Secondly, pay attention to the 12-month deadline for repatriating funds to Vietnam. This period is calculated from the date of the tax finalization report or a legally equivalent document regarding the completion of the project’s liquidation.
- Thirdly, note the 60-day deadline for carrying out procedures in Vietnam. After completing the liquidation and repatriating proceeds, investors have 60 days to execute procedures for terminating the validity of the Outbound IRC or notifying the termination of investment activities, as applicable.
- Fourthly, it is necessary to retain documentation regarding the repatriation of capital to Vietnam. Particularly for projects not subject to the issuance of an Outbound IRC, proof of capital repatriation is a required component of the dossier under Form I.21.
- Fifthly, current foreign exchange regulations must be reviewed. Effective July 31, 2026, Circular 34/2026/TT-NHNN serves as a key document guiding foreign exchange management for outward investment activities and the use of investment capital accounts.
Frequently asked questions
When liquidating an overseas project, from what point is the 12-month deadline for repatriating capital and proceeds to Vietnam calculated?
The 12-month period is calculated from the date of the tax finalization report or a document of equivalent legal validity under the laws of the host country regarding the completion of the project liquidation. Within this period, the investor must repatriate all proceeds from the project liquidation to Vietnam in accordance with regulations.
For an outbound investment project not subject to the issuance of an Outbound IRC, is confirmation from the investment authority required upon termination, or is a notification sufficient?
For projects not subject to Outbound IRC issuance, the investor does not need to follow procedures to terminate the validity of an Outbound IRC. Instead, the investor simply notifies the authorities of the termination of outbound investment activities as prescribed. This is a key distinction to note when applying Decree 103/2026/NĐ-CP.
In which cases is Form I.21 used, and will the dossier be accepted if documentation proving the repatriation of capital to Vietnam is missing?
Form I.21 – Notification of termination of outbound investment activities – is used for projects not subject to Outbound IRC issuance. The dossier must reflect the liquidation status and the repatriation of capital and proceeds to Vietnam; documentation proving the repatriation of capital is a particularly important element. Therefore, enterprises should prepare bank documents, remittance slips, and complete liquidation records before proceeding with the formalities.
Upon project termination, can the enterprise transfer liquidation proceeds directly to its corporate account in Vietnam, or must it use the outward investment capital account?
The investor must comply with regulations regarding outward investment capital accounts. Under Circular 34/2026/TT-NHNN, an investment capital account is an account opened at an authorized bank for a specific project to conduct receipt and payment transactions related to outward investment activities; this includes the recovery of capital, profits, and lawful proceeds from the liquidation or termination of the overseas investment.
Should legal services be used when carrying out the procedure to terminate an outward investment project?
Yes. The procedure for terminating an outward investment project involves investment laws, the liquidation of the overseas project, the repatriation of capital to Vietnam, and foreign exchange management regulations. Utilizing legal services helps enterprises review conditions, prepare documentation, handle capital transfer paperwork, and minimize errors during the process. For projects with significant investment value or those involving complex issues regarding liquidation, taxation, and foreign exchange, enterprises should consider using Viet An Law’s outward investment project termination service to receive comprehensive support throughout the entire process.
For detailed consultation or assistance with the termination of an outward investment project, please contact Viet An Law Firm for the best support.